
2027 Budget Proposal – Key Tax Changes For Indivduals, Companies and Unicorporated Business
Key Takeaway
This Tax Newsletter highlight the key tax measures announced in Budget 2027 affecting individual taxpayers, companies, sole proprietors and partnerships including changes in personal tax relief and corporate income tax rates.
Summary Of 2027 Malaysian Tax Budget
Individual Tax
| No | Current | Proposal | Effective Period |
||||||||||||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 |
Tax Rates for Resident Individual
|
Tax Rates for Resident Individual
|
Effective YA 2027 |
||||||||||||||||||||||||||||||||||||||||||||||
| 2 | Personal tax relief for individual and dependent relatives of RM9,000 per YA | Increased to RM12,000 per YA | Effective YA 2027 |
||||||||||||||||||||||||||||||||||||||||||||||
| 3 |
Tax relief:
|
|
Effective YA 2027 |
||||||||||||||||||||||||||||||||||||||||||||||
| 4 | Tax relief for lifestyle (Restricted to RM2,500) |
The scope is expanded to include:
|
Effective YA 2027 |
||||||||||||||||||||||||||||||||||||||||||||||
| 5 | Tax relief for entrance fees to domestic tourist attractions, cultural and arts programmes (Restricted to RM1,000) | N/A | YA 2027 only |
||||||||||||||||||||||||||||||||||||||||||||||
| 6 | Tax relief for medical treatment expenses for parents and grandparents (Restricted to RM8,000) | The scope for medical care expenses is expanded to include all types of care expenses which must be supported by a written declaration from the carer or a copy of the carer’s work permit together with the relevant receipts, without verification by any registered medical practitioner | Effective YA 2027 |
||||||||||||||||||||||||||||||||||||||||||||||
| 7 | Tax relief for sports related lifestyle for self, spouse, child or parents (Restricted to RM1,000) | The scope is expanded to include purchase of sports shoes (Restricted to RM300) | Effective YA 2027 |
Corporate Tax
| No | Current | Proposal | Effective Period |
||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 |
Tax Rates for Micro, Small and Medium Enterprises (MSMEs)
|
Tax Rates for Micro, Small and Medium Enterprises (MSMEs)
|
Effective YA 2027 |
||||||||||||||||
| 2 |
Capital allowance (AA 100%) is claimable for small value asset (SVA) at RM2,000 each Total capital allowance amount restricted for non-MSMEs is RM20,000 per YA |
|
Effective YA 2027 |
||||||||||||||||
| 3 |
Accelerated capital allowance (IA 20%, AA 40%) on qualifying capital expenditure (QCE) for plant, machinery and ICT equipment as follows:
|
Extended 4 years | For QCE incurred from 1st January 2027 to 31st December 2030 | ||||||||||||||||
| 4 | Salary expenses paid in cash, non-cash or through any other method of payment are tax deductible |
Tax deduction only allowable for salary payments made through financial institutions or cashless payment instruments, except for salary payment transactions by MSMEs. Tax deduction on expenses other than salary payments remains allowable, regardless of the method of payment. |
Effective YA 2028 |
Incentives
| Proposal | Effective Period | |||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
|
Applications received by MIDA from 1 January 2027 |
| Proposal | Effective Period |
|---|---|
|
Full income tax exemption granted to Malaysian shipping companies subject to the following conditions:
|
YA2027 ~ YA2036 |
| Incentive | Proposed Qualifying Activity | Incentive rate | Incentive Period |
|---|---|---|---|
| GITA Project — Tier 1 | Ocean Thermal Energy Conversion | 100% GITA; set-off against 100% or 70% of statutory income | 5 + 5 years |
| GITA Project — Tier 2 |
|
60% GITA; set-off against 70% of statutory income | 5 years |
| Incentive | Proposed Qualifying Activity | Incentive rate | Effective Date |
|---|---|---|---|
| GITA Assets (Own Consumption) – Tier 1 |
(i) Bus, Van, Panel MPV, Movers, Terminal, Tractor, Forklift, Lorry/Light Truck, Lorry and Heavy Vehicle (including prime mover) (ii) Electric vehicle infrastructure (locally produced) (iii) Waste composting and recycling system (locally produced) (iv) Wastewater recycling and rainwater harvesting system (locally produced)
|
100% GITA; set-off against 70% of statutory income | Purchase of qualifying green technology assets verified by MGTC from 1 Jan 2027 to 31 Dec 2030 |
| GITA Assets (Own Consumption) – Tier 2 |
(i) Electric vehicle infrastructure; (ii) Waste composting and recycling system; (iii) Wastewater recycling and rainwater harvesting system.
|
60% GITA; set-off against 70% of statutory income |
Navigating Budget 2027 What Every Business Needs to Know
- Understand the key tax proposals, incentives and policy changes that could impact businesses;
- Identify how the proposed changes could affect your corporate tax position, business costs, cash flow and expansion decisions;
- Get an update on the latest income tax developments and emerging tax policy directions relevant to businesses;
- Gain practical insights to help management plan ahead, manage tax risks and make informed decisions ahead of the Budget 2027 announcement.
Join us to stay informed, plan ahead and be ready for the tax changes that Budget 2027 may bring.
Programme Outline
08.30am – 09.00am
(i) Changes affecting Individuals
– Personal tax reliefs, deductions, and rebates
– Impact on Individual taxpayers and disposable income
(ii) Changes affecting Companies and Non-Companies
– Tax incentives and investment allowances;
– Impact on businesses and investment.
– e-Invoice Compliance Review Framework
– e-Invoice Special Voluntary Disclosure Programme (SVDP)
(i) Stamp duty
(ii) Real Property Gain Tax (“RPGT”) / Capital Gain Tax
(iii) Indirect Taxes (i.e Sales Tax and Service Tax)
(iv) New Taxes
(i) 2023 TP Rules and 2024 TP Guidelines
(ii) Intercompany financing
(iii) 2025 TP Audit Framework
(iv) Pillar 2 requirements
(ii) Proposed new tax incentives
(iii) Extension of time and scope of existing tax incentives
Our Speakers
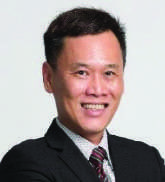
RICHARD OON HOCK CHYE
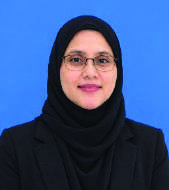
SHEAZANITA BINTI ABD MUTALIB
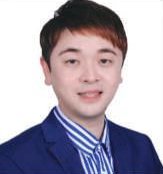
LAI FUNG YAW
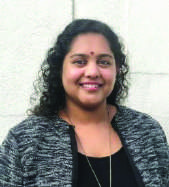
DIVIYA K MOHAN
Contact Us
Payment Details
- For HRDF claim, employers are advised to submit the HRD Corp Grant Application 3-4 weeks in advance to allow sufficient processing time, ensuring Grant Approval is obtained at least 14 days before the training commencement date.
- For direct payment, our invoice will be issued before the training commencement date. Please make payment to “ShineWing TY TEOH Academy Sdn Bhd” . (Bank account no.: Ambank 888 102 463 289 6) either via bank transfer or cheque and thereafter, email the bank remittance advice to us at bank@shinewingtyteoh.com
- Fee includes softcopy training materials and Certificate of Attendance.