
Transfer Pricing Rules 2023 & 2024 Transfer Pricing Guidelines
TP Rules 2023
TP Rules 2023 - Detailed Description
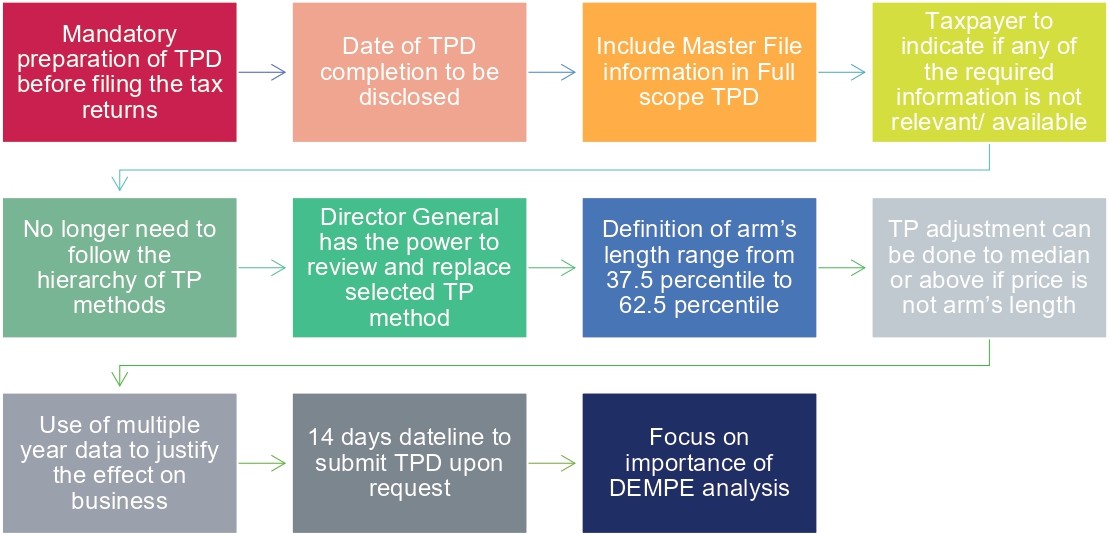
Mandatory preparation of TPD before filing the tax returns
- “Contemporaneous” TPD must be prepared before the filing of the tax return for the relevant year of assessment.
- While this is not a new requirement, it has now been made clearer in the rules and it allows the Tax Authorities to penalize taxpayers who did not prepare the TPD in a timely manner.
- The requirement to include the date of completion in the TPD is in line with the Tax Authorities’ intention to increase compliance and to have concrete written evidence as to whether the TPD was prepared before or after the filing of the tax returns.
- Contemporaneous Full TPD must now include additional information on the MNE Group that is relevant to the taxpayer’s business in Malaysia. Alternatively, the taxpayer can attach the Master file prepared by the Group or ultimate holding company with the Local TPD.
- Previously this requirement was only applicable for Group of Companies that is required to submit the Country-by-Country Report.
- In the absence of any Master File, the local taxpayer will have to request for this information from the ultimate parent company to include in the Local TPD.
- The Tax Authorities have also included a detailed list of information and/or documentation to be included or attached in the Local TPD.
- Based on the above, taxpayers must indicate in the TPD if any of the information or documents required are not applicable to the taxpayers. Failure to do so will result in an incomplete TPD.
- Previously the Guidelines requests taxpayers to select the TP method on a hierarchy basis which means that the Comparable Uncontrolled Price (“CUP”) must be considered first before the other methods on the list.
- However, now the requirement is that the best method is selected and can be supported by explanation and sufficient reasoning to justify the selection.
- There is also a clause that allows the Director General to disregard the taxpayer’s selected method and replace with a different method if they are the opinion that it is not the most appropriate method.
- The Tax Authorities general practice or expectation previously was for taxpayers to achieve results that is above the median of the benchmarking analysis or to make an adjustment to the median of the benchmarking.
- The new rules have included a definition for the arm’s length range from 37.5 percentile to 62.5 percentile and that Companies’ who fall within the range may be regarded as arm’s length.
- However, taxpayers should be aware that the Director General has the power to make any TP adjustment to the median or any other point above median and within the arm’s length range if there is reason to believe that the comparable companies selected is not suitable.
- The Director General may allow for use of data from the review period and prior years if it can be proven that life cycles or business cycles of the property/services are not impacted by the conditions of commercial or financial relations between associated persons.
- However, this can only be used to assist in the selection of comparable and not for the use of multiple year averages.
- Previously this dateline was only included in the TP Guidelines. It has not been included in the Rules as well.
- Failure to submit the TPD within 14 days will result in penalties even if there is no adjustments made or additional taxes payable.
- Emphasizes the importance of the Development, Enhancement, Maintenance, Protection and Exploitation (“DEMPE”) analysis for intangible property.
- Any party that contributes to the functions above should be entitled to an arm’s length consideration, regardless of legal ownership.
TP Rules 2023 – Additional Requirements
Intra-group Services
Intra-group services shall be disregarded if it involves:
- Shareholder or custodial activities
- Duplicative services
- Services that provide incidental benefits or passive association benefits
- On-call services
Cost contribution arrangement
Intangible property
Any party that contributes to the functions above should be entitled to an arm’s length consideration, regardless of legal ownership.
Interest on financial assistance
Any person in a controlled transaction who provides or receives financial assistance (i.e. loan, interest bearing trade credit, advance or debt), directly or indirectly, to or from another person with or without consideration, shall determine the arm’s length interest rate for such assistance.
TP Guidelines 2024
Scope for preparation of CTPD
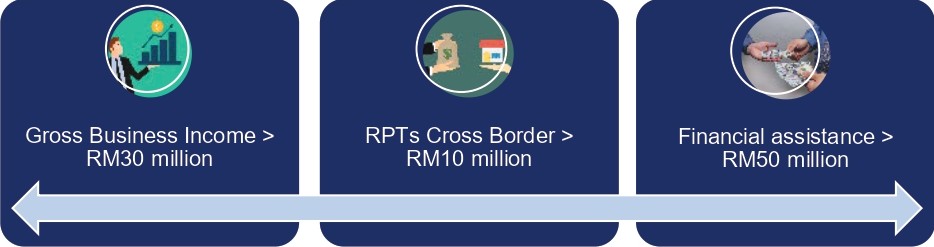
Exemption for preparing transfer pricing documentation
CTPD Flowchart
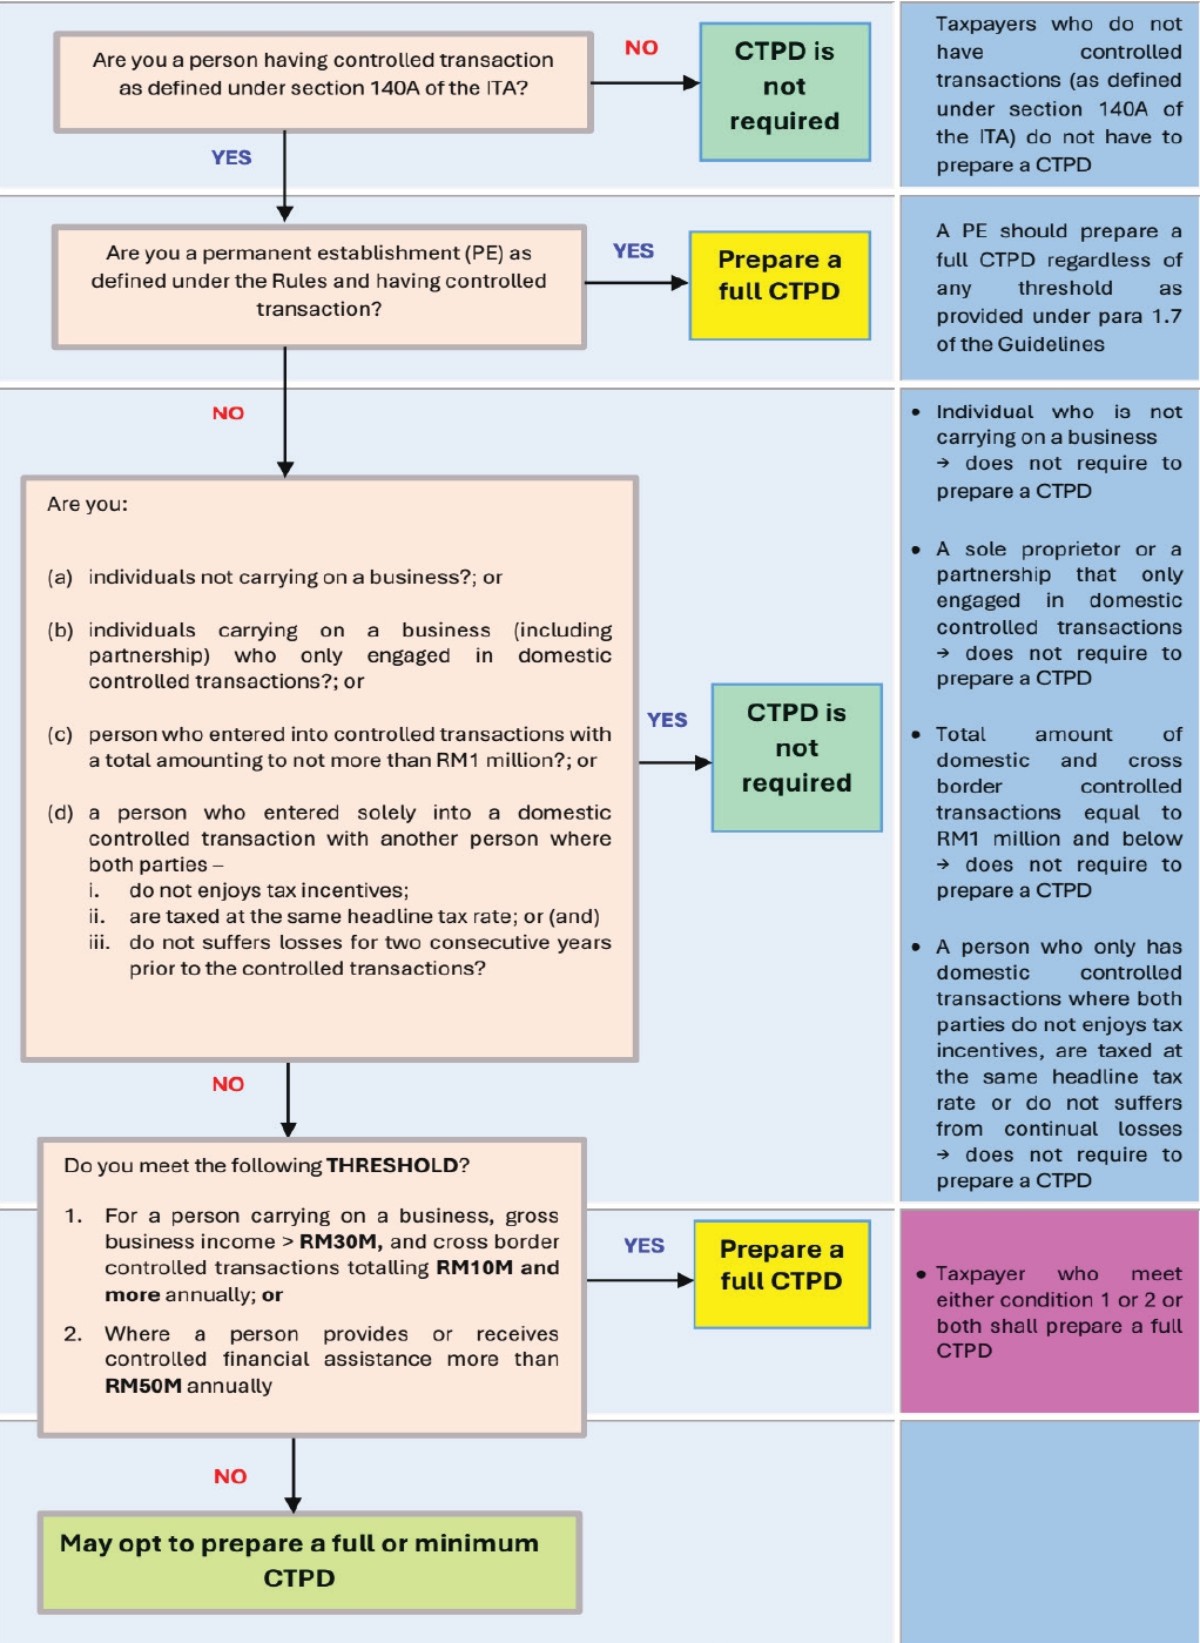
CTPD requirements
Full CTPD Scope
b) Description of MNE Group businesses
c) MNE’s intangible assets
d) MNE’s intercompany financial activities
e) MNE’s financial and tax position
g) Nature of business/industry and market conditions
h) Controlled transactions
i) Pricing policies including formula adopted and sample documents to justify
j) Assumption, strategies and information regarding factors that influenced the price setting policies
k) Functions, assets and risk analysis including risk analysis framework
l) Comparability analysis
m) Selection of the transfer pricing method including basis to justify the selection
n) Application of the transfer pricing method
o) Financial information
p) Other relevant/supporting documents.
Minimal TPD Scope
For minimum CTPD, the scope of controlled transactions and pricing policy is limited to key controlled transactions, which are defined as:
- Transactions related to the taxpayer’s principal business activity, and
- Transactions that, while not principal in nature, individually contribute 20% or more of the taxpayer’s operating revenue for the relevant YA.
The IRB has released a template to simplify TPD compliance and reduce administrative burden of compliance for SMEs (PIN 1/2023). Companies that fall below the threshold can choose to fill in the details requested in the minimum TPD template.
The template is a form that consists of 4 parts as follows:
Company Information
- Company reg no.
- Tax reference
- Address
- Financial period
- Principal activity
- Industry code/ Type of business activity
Group Information
- Name, Country, Address and Tax No. of Ultimate, Holding Subsidiary and Affiliate Companies
- Global and Company organization chart
- Reporting lines
RPTs
- Type, amount of RPT and percentage of transactions
- Name, Country, Business activity, Tax No. and relationship of related companies involved in transaction
- Agreement/ supporting documentation
Policy
- Pricing policy for each type of RPT
- Pricing basis (i.e. costs elements & profit mark-up)
- Sample documentation
- Comparability study
Low value adding intra-group services (“LVAS”)
The service provider shall apply a profit mark-up of 5% to all costs in the pool (expect for any pass- through costs) and the mark-up under this approach does not need to be justified by a benchmarking study. However, all relevant documents should be prepared on the simplified approach.
TP Audit Framework
Key takeaways of the TPTAF 2025 are as follows:
| Key Takeaways | Details |
|---|---|
| Year of assessment | The IRB may carry out a comprehensive audit for up to six (6) YAs. However, the Yas covered to raise the assessment may be extended to seven (7) prior years of assessment, depending on the audit findings. |
| Basis for selection of cases | Basis used in the selection of TP tax audit cases is based on:
|
| Audit settlement | For TP tax audits that only involve related companies in Malaysia, if there are any adjustments made to any of those related companies, the offsetting adjustment for the same amount will not be automatically given to the other related parties. The application for an offsetting adjustment must be made by the other related parties, and audits will be carried out to ensure that the application may be considered on the provisions of the Act. |
| Voluntary disclosure | Voluntary disclosures are made after the deadline for submission of the Return Form but before the audit commences. The information and documentation required, along with the Voluntary Disclosure Form to be submitted is set out and included in the TPTAF 2025. |
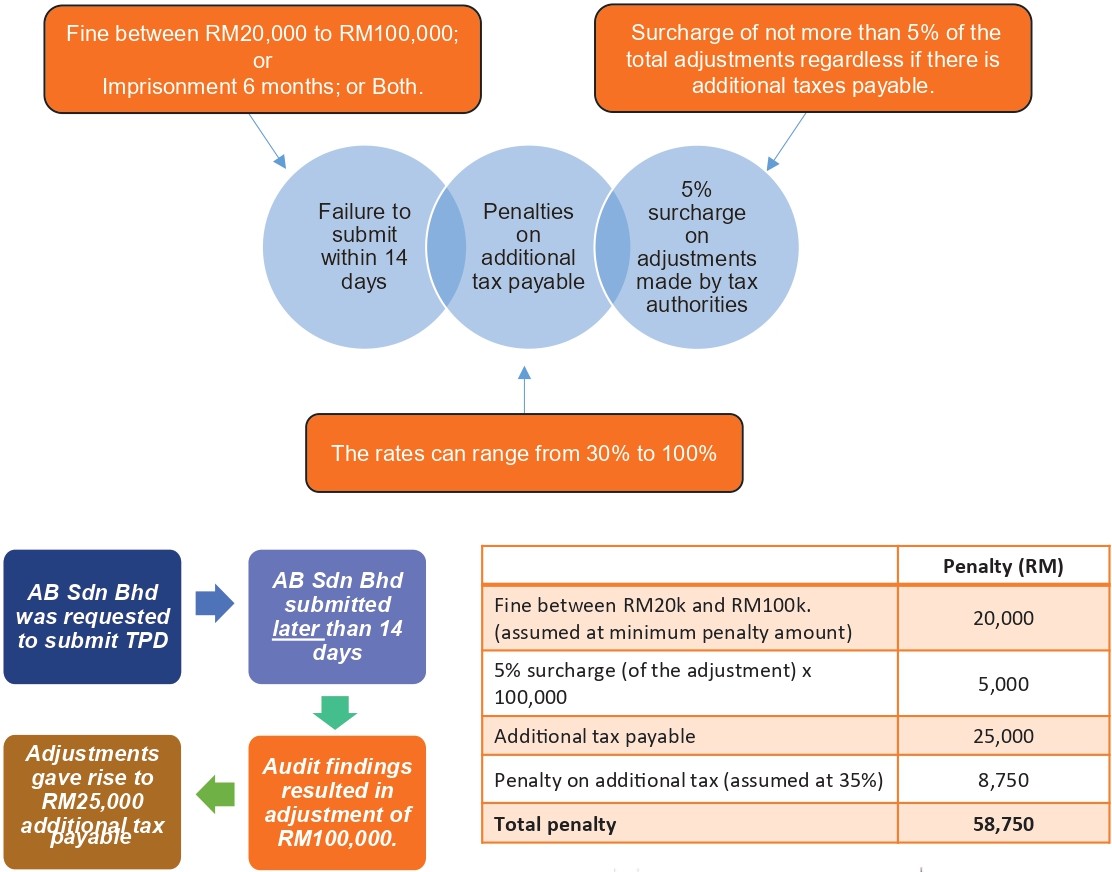
| Offence, penalty and surcharge | A surcharge at a rate of up to 5% on the amount of the transfer pricing adjustment may be imposed instead (0% to 4% for a voluntary disclosure). A surcharge still may be imposed even if no additional assessment is raised because the surcharge rate is imposed on the amount of the adjustment itself. |
Penalty
From the year of assessment 2023, a taxpayer who fails to submit a TPD within 14 days from the date of service of a written notice has committed an offence under subsection 113B(1) of the ITA. The taxpayer may be fined not less than RM20,000.00 and not more than RM100,000.00 or imprisonment for not more than 6 months or both.
The amount of penalty that will be imposed based on the period of delay in submitting the TPD is as follows:
| No | Period of delay (number of days) | Penalty amount |
|---|---|---|
| 1 | Up to 7 days | RM20,000.00 |
| 2 | More than 7 days up to 14 days | RM40,000.00 |
| 3 | More than 14 days up to 21 days | RM60,000.00 |
| 4 | More than 21 days up to 28 days | RM80,000.00 |
| 5 | More than 28 days | RM100,000.00 |
Illustration on Penalties
Income Tax (Country-by-Country Reporting) Rules 2016 (“CbyCR Rules”)
The Rule is applicable to MNE Groups that fulfil the following criteria:
- RM 3 Billion
Ultimate holding entity; or
Incorporated under the companies act 2016; or
Surrogate holding entity; or
Permanent establishment in Malaysia.
- RM 3 Billion
-
Labuan entity carrying on a Labuan business activity.
Timeline
Penalty under Section 112A & 113A of the ITA and Labuan Regulations
| Income Tax (CbyCR) Rules 2016 | Labuan Business Activity Tax (CbyCR) Regulations 2017 |
|---|---|
Failure of submission/Incomplete and/or incorrect information provided to the DGIR:
|
Failure of submission/Incomplete and/or incorrect information provided to the DGIR:
|
Malaysian parent entities and subsidiaries submitting the Form C , TR , TA , TC or TN (tax return forms, whichever is applicable) can furnish the notification by way of tax returns while companies filing Form LE & TF are required to furnish the notification using a manual notification form as follows:
| Reporting entity [Annex B1] |
The reporting entity shall notify the Director General in writing if it is the ultimate holding entity on or before the last day of the FY. Details of all Malaysian and foreign non-reporting constituent entities must be included. |
|---|---|
| Non-reporting entity [Annex C1 & C2] |
The Malaysian subsidiary must notify the Director General in writing of the identity and tax residence of the reporting entity on or before the last day of the FY. |
Tax Return Form
-
Transfer Pricing Documentation and its related information
Tax payer is to disclose its characterization, other related information and all type of transactions they are involved in with a related party and the amount.
-
Disclosure of whether the taxpayer is subject to interest restriction under Section 140C.
Tax authorities introduced Restriction on deductibility of interest under Section 140C of the Income Tax Act 1967, effective 1 July 2019 onwards aimed at restricting the deduction of interest expense in relation to cross border transaction. The Rules are applicable to:
- companies who have been granted any financial assistance in a controlled transaction;
- the total amount of any interest expense for all such financial assistance exceeds RM500,000 in the basis period.
The maximum amount of interest that is deductible is 20% of the Tax EBITDA. The balance is allowed to be carried forward.
-
Disclosure on CbyCR
Tax payer is to disclose if CbyCR is relevant for the Group and fill in the relevant information of the reporting entity.
Key Take-aways
- Tax authorities may enforce a tax audit at any time of the year.
- Tax authorities have provided a time and cost-efficient template for SME companies to encourage
- compliance.
- In addition to the template, taxpayers also need to include documentation or analysis to justify that
- the RPT is carried out at market price (i.e. comparability study)
- It is essential for the taxpayers to indicate the completion date on the TPD.
- Although there are exemptions for the preparation of TPD, in case of an audit, there are possibilities for
- adjustments that will result in additional tax.
- There is a risk of IRB imposing the 5% surcharge on adjustments on top of penalty imposed.
- Taxpayer’s responsibility is to maintain the relevant records, documentation and calculation to justify
- the arm’s length nature of the inter-company transactions.
- Taxpayers need to reassess the completeness and robustness of the TPD prepared previously and
- make amendments to the scope where necessary.
- Taxpayers should ensure contemporaneous preparation of the TPD.