Categories
Ideas & Insights Newsletter Tax

At What Point Is Social Media Income Taxable

Tax

Key Takeaway

Influencer income is taxable under Section 4(a) of the ITA, whether received in cash or in kind, and whether from local or overseas platforms.
With the rapid growth of the creator economy, the Inland Revenue Board of Malaysia (“IRBM”) has issued the Guidelines on the Tax Treatment of Income Derived by Social Media Influencers on 14 January 2026, providing clearer guidance on how income arising from influencer activities is treated for income tax purposes.

Income earned through social media cannot be overlooked simply because it is received through digital platforms, paid by overseas companies, or provided in non-cash form. From platform monetisa- tion and brand sponsorships to promotional fees, free products and other benefits, influencers may have income tax obligations that extend well beyond their cash receipts. This Tax Newsletter highlights the key tax considerations under the Guidelines.

Who Is a Social Media Influencer for Tax Purposes?

Under the Guidelines, an individual may be regarded as a social media influencer if they use their influence, knowledge, position or relationship with users to influence others through social or digital media. In simple terms, the Guidelines may apply to individuals who use social media to create content, promote products or services, or generate income through their online influence.

Influencer activities may include:
content-icon

Creating content

producing, recording, publishing, uploading or displaying written, audio or video content.
appearance-icon

Making appearances

participating in programmes, activities or events through social media.
Promoting-icon

Promoting products or services

advertising, endorsing or marketing products or services online.
income-icon

Receiving income or benefits

earning money or receiving gifts, products, services or other benefits from social media activities.
The Guidelines recognise two broad categories of social media influencers:
Category Examples Tax Treatment
Individual Influencer Artistes, athletes, professionals, students, homemakers and other content creators Income earned by individual influencers is generally treated as business or professional income under Section 4(a) of the ITA. This applies whether the income is earned under a formal contract or an informal arrangement.
Object-Based Influencer Animated or cartoon characters; film or drama characters; logos, symbols; or names associated with an organisation or company
(Eg; Upin & Ipin and BoBoiBoy)
The account or character owner receiving the income is generally subject to tax.

If the copyright owner and account owner are different, the tax applies to the party that ultimately receives the income.

Types of Income Subject to Tax

Income Type Examples
Social Media Monetisation Payments based on views, likes, followers, advertisements, subscriptions and clicks
Brand Collaborations Sponsorship, endorsement, promotional and campaign fees
Sale of Products Merchandise and other products sold through social media
Sale of Social Media Accounts Sale or transfer of social media accounts or IDs
Royalties Royalties from characters or content used on social media
Non-Cash Benefits Free products, services, vouchers, discounts and other benefits
Income from Overseas Platforms Payments received from foreign social media platforms
Overseas Promotional Activities Promotional work carried out overseas as part of the influencer's Malaysian profession

Claimable expenses

Influencers may claim tax deductions under Section 33(1) of the Income Tax Act 1967 (“ITA”) for expenses wholly and exclusively incurred in generating their influencer income. These may include internet and data costs, filming and editing fees, content production costs and other expenses directly related to the influencer’s income-generating activities.

Capital Allowance

Influencers may claim capital allowances under Schedule 3 of ITA on qualifying assets used in their influencer activities, such as cameras, lighting equipment and other content production equipment, subject to the applicable conditions.
Categories
Ideas & Insights Newsletter Tax

RM3 Million e-Invoice Exemption Threshold: Eligible Taxpayers May Discontinue e-Invoice Issuance Without Prior HASiL Approval

Tax

Key Takeaway

  • The e-Invoice implementation threshold has been increased from RM1 million to RM3 million, effective 1 September 2026.
  • Taxpayers who have already started e-Invoicing but now qualify for the exemption may stop issuing e-Invoices without applying to HASiL.
The Inland Revenue Board of Malaysia (“IRBM”) has clarified that businesses with annual turnover or revenue below RM3 million that satisfy the prescribed exemption criteria will not be subject to compliance action or penalties, even if they have not issued e-Invoices from their applicable implementation date. The clarification was provided in the latest e-Invoice Frequently Asked Questions (FAQ) issued by IRBM dated 4th August 2026.

Immediate Cessation of e-Invoice Without Prior Approval

Taxpayers who qualify for the e-Invoice exemption but have already commenced e-Invoice implementation may discontinue issuing e-Invoices immediately. Importantly, taxpayers are not required to submit a separate application to IRBM or obtain prior approval to cease e-Invoice implementation.

Under the latest clarification, taxpayers with annual turnover or revenue below RM3 million who satisfy the exemption conditions set out in Section 1.6.10 of the e-Invoice Guideline are eligible for the exemption.

Voluntary e-Invoice Implementation Remains an Option

Businesses that qualify for the exemption are not prohibited from continuing with e-Invoice implementation. Taxpayers may voluntarily continue issuing e-Invoices if they consider it beneficial for their business operations, accounting processes or broader digitalisation efforts.

Tax Incentives

The e-Invoice FAQs also summarise the tax incentives available to eligible taxpayers in relation to e-Invoice implementation, including Accelerated Capital Allowance (ACA) incentives. The applicable incentives, together with their legislative reference or status, key details, and effective period, are set out in a table.

Special Voluntary Disclosure Programme (“SVDP”)

FAQs No 123–133 provide taxpayers with greater certainty on the practical application of the e-Invoice SVDP, particularly in relation to historical rectification, the 72-hour cancellation rule, incorrect classifications, subsequent disclosures, consolidated e-Invoices, group entities and third-party service providers. Taxpayers should consider undertaking a review of their historical e-Invoice transactions to identify any outstanding non-compliance and, where appropriate, regularise the position during the SVDP period ending 31 December 2027.
Categories
Ideas & Insights Newsletter Tax

Employee Secondment Is Free From Service Tax Subject To Certain Conditions

Tax

Key Takeaway

A secondment arrangement is not automatically non-taxable. Its Service Tax treatment depends on whether the applicable conditions for a genuine secondment are satisfied.

Tips

  • Review your existing employee secondment arrangements to ensure they meet the conditions under Ketetapan Umum Bil. 5/2026;
  • Identify arrangements that do not meet the prescribed conditions and assess whether Service Tax should be charged on the relevant employment services.
Under the 2024 Guide on Employment Services, employment services are generally subject to Service Tax. However, employee secondment is excluded from the scope of taxable employment services.

With the issuance of General Ruling Bil. 5/2026, Customs has now clarified what qualifies as an employee secondment. In simple terms, a secondment arrangement will not be subject to Service Tax only if all the prescribed conditions are met.

A secondment arrangement will be regarded as non-taxable services only if all of the following conditions are satisfied:

Appropriate contractual documentation

The arrangement should be supported by a formal secondment agreement or other relevant documentation evidencing the nature and terms of the secondment;

Original employer is not an employment-service provider

The original employer’s business must not be the provision of employment services, including an employment agency or professional employer organisation;

Temporary transfer

The employee is temporarily transferred to perform duties for another company for a specified period and subsequently returns to the original employer;

Continuing employment relationship

The employee remains employed by the original employer, with the employment relationship continuing throughout the secondment;

Exclusive service during secondment

During the secondment period, the employee works solely for the host company;

Control by the host company

The host company has overall control over the employee’s work and duties during the secondment; AND

Salary / allowances recovered at cost only

The host company bears the employee’s remuneration and relevant allowances, whether paid directly or indirectly, without an additional service fee, commission or mark-up.
Categories
Ideas & Insights Newsletter Tax

e- Invoice: RM3 Million Is the New Threshold!

Tax

Key Takeaway

e-Invoice exemption threshold increased from RM1 million to RM3 million, effective 1 September 2026.

Tips

  • Check your annual turnover/revenue against the RM3 million threshold.
  • Check ownership and group structures before relying on the exemption, particularly shareholders, holding companies, related companies and joint ventures.
The Inland Revenue Board of Malaysia (“IRBM”) issued e-Invoice Guideline Version 4.8 on 30 August 2026, replacing Version 4.7 dated 7 July 2026. The key amendments relate principally to the e-Invoice implementation timeline and the exemption threshold for taxpayers with annual turnover or revenue below RM3 million.

This represents a significant relaxation for taxpayers with turnover between RM1 million and below RM3 million, who were previously within the e-Invoice framework.

The amendments comprise changes to paragraphs 1.5 and 1.6.1(e), together with the introduction of new paragraphs 1.6.9 and 1.6.10 as below:

Implementation timeline for new businesses

Paragraph 1.5 has been amended to reflect the revised RM3 million threshold in determining the e-Invoice implementation timeline for businesses that commence operations between 2023 and 2025. Businesses that commenced operations during this period should reassess their e-Invoice implementation date based on the revised RM3 million threshold.

Exemption threshold increased

The exemption threshold has been increased from RM1 million to RM3 million.

Specific taxpayers brought into the e-Invoice requirement

This Guide further clarifies the e-Invoice treatment applicable to the following entities:

  • Statutory bodies;
  • Statutory authorities;
  • Local authorities; and
  • International organisations.

These entities are required to issue e-Invoices for goods sold or services performed from 1 July 2025 onwards.

Conditions restricting the RM3 million exemption

The exemption for taxpayers with annual turnover / revenue of less than RM3 million applies across taxpayer categories, including individuals, partnerships, companies and cooperatives. However, the exemption does not apply in certain ownership or group-structure circumstances:-

Taxpayer with annual turnover or revenue of less than RM3 million shall not be eligible for the exemption where any of the following conditions apply:

  • Non-individual shareholder
    The taxpayer has a non-individual shareholder (or equivalent) with annual turnover / revenue of RM3 million or more.
  • Subsidiary
    The taxpayer is a subsidiary of a holding company whose annual turnover / revenue is RM3 million or more.
  • Related company / joint venture
    The taxpayer has a related company or joint venture with annual turnover / revenue of RM3 million or more.
Categories
Ideas & Insights Newsletter Tax

Employment Service: Fees Subject Service Tax While Salary Recoveries, Disbursement Costs & Statutory & Regulatory Charges Are Excluded

Tax

Key Takeaway

Service Tax applies only to employment or management fees, excluding disbursement expenses.

Tips

To ensure that fees and disbursements are clearly stated and properly supported by documentation.
The Royal Malaysian Customs Department (“RMCD”) issued a new announcement on 13 August 2026, clarifying the Service Tax treatment of employment services, particularly with regard to employment / management fees and disbursement expenses.

Under the RMCD’s clarification:

  • Employment or Management fees
    Service Tax applies to the fees charged for the provision of employment services and management services;
  • Disbursement Costs
    Costs or expenses incurred on behalf of a customer and subsequently recovered on a pass-through (disbursement) basis are not subject to Service Tax;
  • Statutory and regulatory charges
    Fees, duties, levies, taxes, fines, penalties and other similar payments imposed under written laws and paid on behalf of the customer are treated as disbursements. These amounts should not be included in the taxable value for Service Tax purposes.
Categories
Ideas & Insights Newsletter Tax

Employment Contracts of RM3,000 and Below No Longer Require IRBM Endorsement

Tax

Key Takeaway

Not every employment-related document needs to be stamped.

Tips

Check the employment contract and related documents against the applicable category to determine whether stamp duty payment, stamping, or endorsement is required.
The Inland Revenue Board of Malaysia (“IRBM”) issued a media release on 7 August 2026 providing important guidance on stamp duty for employment contracts, including the applicable exemptions and endorsement requirements under the Stamp Act 1949.

At a Glance: Do You Need to Stamp Your Employment Documents

Employment Document / Situation What Employers Need to Do
Employment contract with monthly salary of RM3,000 or below. No stamping and no endorsement required.
Employment contract with monthly salary above RM3,000. Stamp and endorse only the main/master employment contract.
Supporting employment documents relating to the same employment. No stamping and no endorsement required.
Instrument covered under the “General Exemption” category. No stamp duty payable, but endorsement is required.
For more details, please click the link below:
Media Release dated 07 August 2026
Categories
Ideas & Insights Newsletter Tax

Stamp Duty – Special Voluntary Disclosure Programme

Tax

Key Takeaway

  • Responsibility for stamp duty assessment is now placed on taxpayers.
  • Taxpayers are afforded the chance to regularize unstamped instruments and seek remission of penalties.
Many businesses are unaware that certain agreements — including loan agreements, service contracts and shareholders’ agreements — may be subject to stamp duty. The introduction of the Stamp Duty Self-Assessment System and the Special Voluntary Disclosure Programme makes it timely for businesses to review their documenta- tion and ensure compliance.

Stamp duty is a tax imposed on certain of written instruments specified in the First Schedule of Stamp Duty Act 1949 (“SA”) and not on the underlying transactions themselves.

There are two main categories of stamp duty:

  1. Ad valorem duty – calculated based on the type and value of the instrument; and
  2. Fixed duty – imposed at a prescribed amount, typically starting from a nominal sum of RM10 per instrument.

STAMP DUTY SELF-ASSESSMENT SYSTEM (SDSAS)

Effective from 1 January 2026, the Inland Revenue Board of Malaysia (“IRBM”) has implemented the Stamp Duty Self-Assessment System. The implementation will be carried out in phases as follows:-
Phase Effective Date Type of Instruments
Phase 1 From 1 January 2026 Instruments or agreements relating to rentals or leases, general stamping and securities.
Phase 2 From 1 January 2027 Instruments for transfer of property ownership.
Phase 3 From 1 January 2028 Instruments or agreements not covered under Phase 1 and Phase 2.

RESPONSIBITIY OF DUTY PAYERS

Under SDSAS, taxpayers are responsible for determining, calculating and declaring stamp duty obligations. For instruments executed in Malaysia, they must be stamped within 30 days of the date of execution. For instruments executed outside Malaysia, the instrument must be stamped within 30 days from the date it is first received in Malaysia.

Taxpayers are also required to retain the stamped instruments and all related supporting documents for a minimum period of seven (7) years to ensure proper compliance and to facilitate any audit by IRBM.

PENALTIES

Late Stamping
Period of Delay in Stamping Penalties
Not exceeding 3 months RM50 or 10% of the duty amount (whichever is higher)
Exceeding 3 months RM100 or 20% of the duty amount (whichever is higher)
Executing or Signing Unstamped Documents
Any person who executes or signs an instrument that has not been duly stamped may be liable to a fine of not less than RM1,000 and not exceeding RM10,000

SPECIAL VOLUNTARY DISCLOSURE PROGRAMME (“SVDP”) FOR STAMP DUTY

On 28th January 2026, the IRBM has announced a Special Voluntary Disclosure (‘SDVP’) for stamp duty and published a set of Frequently Asked Questions (“FAQs”) in relation to SVDP on its website.

During SDVP period from 1 January 2026 to 30 June 2026, all instruments executed from 1 January 2023 to 31 December 2025 may qualify for penalty exemption under Section 47A(2), Stamp Act 1949, subject to relevant conditions.

Key Points from the FAQ

  1. Instruments executed between 1 January 2023 and 31 December 2025 are eligible for SVDP 2026, provided that stamping and payment of stamp duty payment are completed between 1 January 2026 and 30 June 2026;
  2. Eligible for SDVP 2026:-
Stamping Submission Date Status of Stamp Duty Payment Status of Penalty
Before 1 January 2026 Fully paid (including penalties) Not eligible for SDVP
Before 1 January 2026 No payment made within the SVDP period Penalty not waived
1 January 2026 – 30 June 2026 Payment made within the SVDP period Penalty waived
  1. No appeal application is required and penalty will be automatically waived once the stamp duty is paid between 1 January 2026 to 31 December 2026;
  2. All instruments executed between 1 January 2023 and 31 December 2025 and stamped under SVDP 2026 will not be subject to audit. However, SVDP does not prevent the IRBM from auditing other instruments not disclosed under the SVDP;
  3. Cases involving fraud are excluded from the SVDP programme.
The FAQs are available in Bahasa Malaysia and can be downloaded from the IRBM’s official website:-
FAQs

Action Points for Business

Businesses should consider taking the following steps:
1. Conduct an Internal Review of Documents
Businesses should review all contracts and written instruments executed between 1 January 2023 and 31 December 2025 to determine whether they are subject to stamp duty but have not been stamped.

Common examples include:
  • Rental or tenancy agreements
  • Service agreements
  • Loan agreements between companies or related parties
  • Shareholders’ agreements
  • Security documents (charges, debentures, guarantees)
  • Memorandum of understanding (MOU) with binding terms
  • Settlement agreements

2. Identify Unstamped or Late-Stamped Instruments
Businesses should identify documents that:
  • have not been stamped, or
  • were stamped after the statutory deadline.

These may qualify for penalty exemption under the SVDP if disclosed within the programme period.

3. Take Advantage of the SVDP Window
Where unstamped instruments are identified, businesses should submit the documents for stamping and pay the applicable stamp duty before 30 June 2026 to enjoy full penalty waiver.

4. Strengthen Internal Compliance Procedures
With the implementation of SDSAS, businesses should implement internal procedures to ensure that:
  • new agreements are reviewed for stamp duty implications;
  • stamping deadlines are monitored; and
  • supporting documentation is properly maintained.

5. Seek Professional Advice Where Necessary
Businesses that are uncertain whether a document is subject to stamp duty should seek professional advice, as incorrect stamping or failure to stamp instruments may result in penalties.
If you would like assistance in reviewing your agreements or determining whether any instruments require stamping, please feel free to contact us.
Categories
Ideas & Insights Newsletter Tax

e-Invoicing Updates

Tax

Key Takeaway

  • Phase 4 e-Invoicing: 12-Month Transition Period
  • Special Concession for the Construction Materials Sector

A. 12 - MONTH TRANSITIONAL PERIOD (1 JANUARY – 31 DECEMBER 2026)

As you are aware, businesses with annual turnover between RM1 million and RM5 million fall under Phase 4 of the e-Invoice programme and is required to fully implement e-invoicing effective from 1 January 2026.

With reference to the Media Release issued by Inland Revenue Board of Malaysia (“IRBM”) dated 5th January 2026, the Government has announced a 12-month interim relaxation period for businesses under Phase 4, extending the previously announced 6-month timeline.

With that, the interim relaxation period for such businesses has been extended to 1 January 2026 to 31 December 2026. What is important to note is that this is not a postponement of the requirement for businesses under Phase 4 to be fully-compliant with the e-Invoice system – it is merely a deferment. During this period, businesses under Phase 4 will still be required to comply with the conditions spelt out in the IRBM’s e-Invoice Specific Guidelines, for e-Invoice compliance during the interim relaxation period.
During the interim relaxation period which spans 1 January 2026 to 31 December 2026, business under Phase 4 are permitted to do the following:

a. Issue consolidated e-Invoices for all activities and transactions, including for industries or activities listed under Section 3.7 of the Specific Guidelines on e-Invoices. Issuance of consolidated e-Invoices is also permitted even if there is an e-Invoice request from the buyer;

b. Issue consolidated self-billing e-Invoices for all self-billing situations as outlined under Section 8.3 of the Specific Guidelines on e-Invoices; and

c. Allow any transaction description to be entered in the “Product or Service Description” field.

During the transition period, the IRBM has announced that they will not impose penalties for any non-compliance with the e-Invoice requirements, provided that the taxpayer complies with the rules stated above.

B. SPECIAL CONCESSION: CONSTRUCTION MATERIALS SECTOR

Effective 1 January 2026, the government also agreed to allow taxpayers from the wholesale and retail of construction materials sector to issue consolidated e-Invoices. However, e-Invoices are still mandatory if they involve transactions exceeding RM10,000 or more or when there is a request from the buyer to obtain an e-Invoice.
For more details please refer to the link below:-
Media Release from IRBM dated 5 Jan 2026

How We Can Help

At ShineWing, we provide a wide spectrum of services to support your successful implementation of the e-Invoice system in Malaysia and compliance of its laws and guidelines, among which, include the following:

Regulatory Guidance

Supporting businesses in interpreting and complying with IRBM’s e-invoicing requirements, including IRBM guidelines, statutory deadlines, and documentation standards to ensure full tax compliance..

Ongoing Support

Providing continuous maintenance, governance, and updates to keep e-invoicing solutions aligned with evolving IRBM regulations, while offering training and advisory to sustain compliance and operational efficiency.
Should you have any questions or require any assistance on the above, please do not hesitate to drop us an email or call us.
Categories
Ideas & Insights Newsletter Tax

Mandatory e-Invoicing System Starting From June 2024

Tax

Key Takeaway

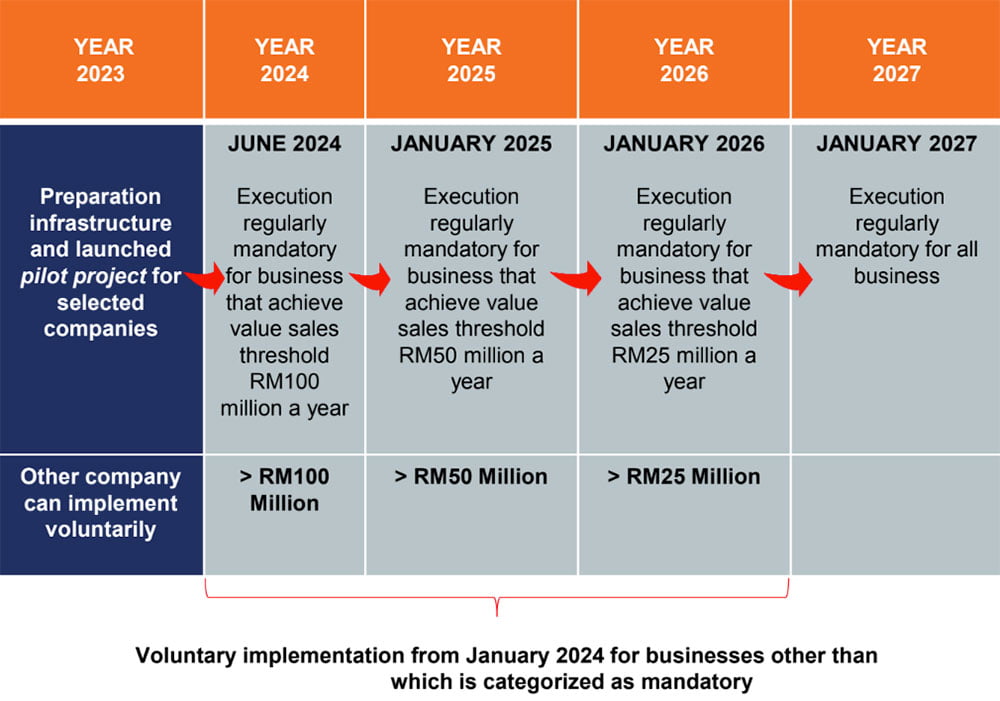
E- Invoicing system to be implemented in phases beginning from 2024.
On 25th October 2022, the Malaysian Digital Economy Corporation (MDEC) signed a Memorandum of Understanding (MoU) with the Inland Revenue Board of Malaysia to implement the National e- Invoicing system. This electronic invoicing will first effect B2B transactions and will begin with pilot phase in January 2024 with selected companies.

WHAT IS e-INVOICING?

e-Invoicing is the exchange of electronic invoice documents in digital format between the supplier and the buyer. These documents or data can then be uploaded into the platform managed by IRBM. Thereafter, the data will be extracted and pre-filled into the taxpayer’s income tax form.

e-Invoice is NOT an invoice issued in PDF, HTML, JPG or other formats but a digital invoice created by the seller and transferred electronically to the buyer’s system.

WHAT ARE THE BENEFITS OF e-INVOICING?

  • Greater transparency to the tax authorities and reduce administrative cost to both tax authorities and taxpayers especially during tax audits;
  • Improve the tax compliance, more efficient financial and tax reporting;
  • Will reduce the burden of record keeping by taxpayers, as taxpayers will no longer need to keep physical copies of their receipts, invoices, and vouchers for seven years as currently required under Section 82A(1) and Section 82A(2) of the Income Tax Act 1967.
  • Savings of resources (time and salary costs) as businesses no longer to manually input data or scan invoices into their systems.

IMPLEMENTATION OF e-INVOICING:

Implementation of e-invoicing
Taxpayers are advised to get ready for the imminent implementation of e-Invoice which will affect all businesses, come January 2027. While waiting for further updates from the authorities on the technical and infrastructure requirements of implementing the e-Invoice system, businesses should now evaluate their ability of their current accounting and ERP systems to cater for the e-Invoice system as well as the relevant initiation and authorisation processes of the e-Invoice cycle, as such e-Invoice, in its stream of digital data, is a valid legal document.
Categories
Ideas & Insights Newsletter Tax

Special Voluntary Disclosure Programme (SVDP) 2.0

Tax

Key Takeaway

Special Voluntary Disclosure Programme from 1 June 2023 to 31 May 2024 by the Inland Revenue Board of Malaysia (IRBM) and Royal Malaysian Customs Department (RMCD) with a 100% waiver of penalty

Special Voluntary Disclosure Programme (SVDP) 2.0 (Direct Tax)

In the recent 2023 Malaysian Budget announcement on February 24, 2023, the Prime Minister Datuk Seri Anwar Ibrahim announced the reintroduction of Special Voluntary Disclosure Program 2.0 (“SVDP2.0”) to be carried out by both the Inland Revenue Board of Malaysia (IRBM) and Royal Malaysian Customs Department (RMCD). This program is offered to encourage taxpayers to make voluntary disclosures in reporting their FULL income and pay taxes within a stipulated period.

This newsletter focuses on the SDVP2.0 by IRBM. The guidelines on this special program will be issued by IRBM soon.

Proposed Measures of the SVDP 2.0:
The SVDP is proposed to be available for a period of 12 months, from June 1, 2023, to May 31, 2024.

Based on the proposed measures, the SVDP would cover both direct and indirect taxes. However, the SVDP2.0 does not apply to cases that are currently undergoing auditor investigation.