Categories
Ideas & Insights Newsletter Tax

RM3 Million e-Invoice Exemption Threshold: Eligible Taxpayers May Discontinue e-Invoice Issuance Without Prior HASiL Approval

Ideas & Insights

Key Takeaway

  • The e-Invoice implementation threshold has been increased from RM1 million to RM3 million, effective 1 September 2026.
  • Taxpayers who have already started e-Invoicing but now qualify for the exemption may stop issuing e-Invoices without applying to HASiL.
The Inland Revenue Board of Malaysia (“IRBM”) has clarified that businesses with annual turnover or revenue below RM3 million that satisfy the prescribed exemption criteria will not be subject to compliance action or penalties, even if they have not issued e-Invoices from their applicable implementation date. The clarification was provided in the latest e-Invoice Frequently Asked Questions (FAQ) issued by IRBM dated 4th August 2026.

Immediate Cessation of e-Invoice Without Prior Approval

Taxpayers who qualify for the e-Invoice exemption but have already commenced e-Invoice implementation may discontinue issuing e-Invoices immediately. Importantly, taxpayers are not required to submit a separate application to IRBM or obtain prior approval to cease e-Invoice implementation.

Under the latest clarification, taxpayers with annual turnover or revenue below RM3 million who satisfy the exemption conditions set out in Section 1.6.10 of the e-Invoice Guideline are eligible for the exemption.

Voluntary e-Invoice Implementation Remains an Option

Businesses that qualify for the exemption are not prohibited from continuing with e-Invoice implementation. Taxpayers may voluntarily continue issuing e-Invoices if they consider it beneficial for their business operations, accounting processes or broader digitalisation efforts.

Tax Incentives

The e-Invoice FAQs also summarise the tax incentives available to eligible taxpayers in relation to e-Invoice implementation, including Accelerated Capital Allowance (ACA) incentives. The applicable incentives, together with their legislative reference or status, key details, and effective period, are set out in a table.

Special Voluntary Disclosure Programme (“SVDP”)

FAQs No 123–133 provide taxpayers with greater certainty on the practical application of the e-Invoice SVDP, particularly in relation to historical rectification, the 72-hour cancellation rule, incorrect classifications, subsequent disclosures, consolidated e-Invoices, group entities and third-party service providers. Taxpayers should consider undertaking a review of their historical e-Invoice transactions to identify any outstanding non-compliance and, where appropriate, regularise the position during the SVDP period ending 31 December 2027.
Categories
Ideas & Insights Newsletter Transfer Pricing

Transfer Pricing Rules 2023 & 2024 Transfer Pricing Guidelines

Ideas & Insights

TP Rules 2023

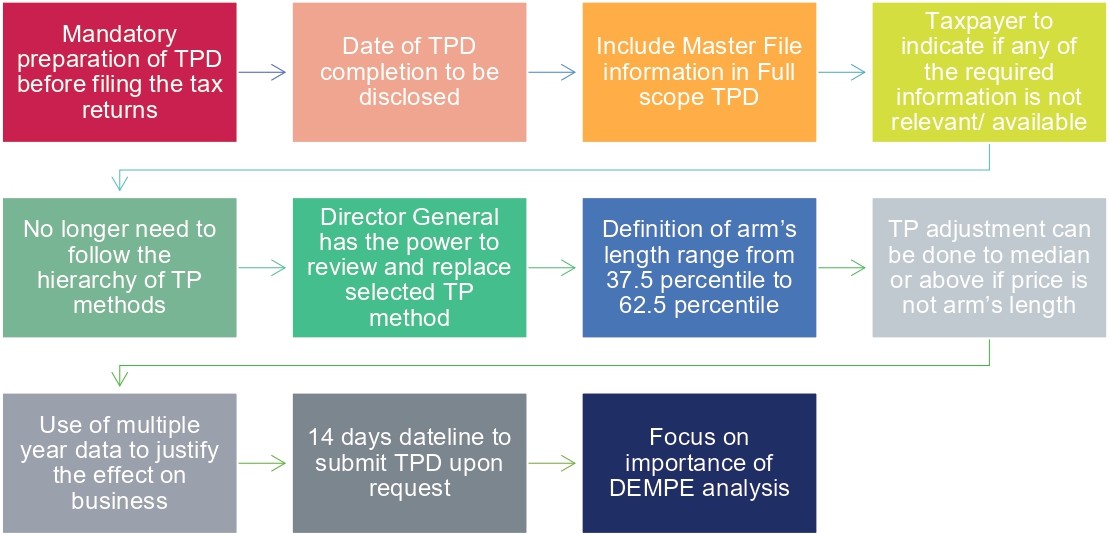
The Income Tax (TP) Rules 2023 (“2023 TP Rules”) were officially released and gazetted on 29 May 2023.The rules were issued by the Ministry of Finance and the Inland Revenue Board of Malaysia (“IRBM”). They came into operation starting from the Year of Assessment (“YA”) 2023 and it supersedes the rules that was released in 2012. Significant changes were made with the intention to boost compliance and provide taxpayers with more clarity with regards to TP compliance. Some of the important changes that affect the way TP documentations (“TPD”) will be prepared moving forward is as follows

TP Rules 2023 - Detailed Description

Mandatory preparation of TPD before filing the tax returns

Date of TPD completion to be disclosed
  • “Contemporaneous” TPD must be prepared before the filing of the tax return for the relevant year of assessment.
  • While this is not a new requirement, it has now been made clearer in the rules and it allows the Tax Authorities to penalize taxpayers who did not prepare the TPD in a timely manner.
  • The requirement to include the date of completion in the TPD is in line with the Tax Authorities’ intention to increase compliance and to have concrete written evidence as to whether the TPD was prepared before or after the filing of the tax returns.
Include Master File information in Full scope TPD
Taxpayer to indicate if any of the required information is not relevant/ available
  • Contemporaneous Full TPD must now include additional information on the MNE Group that is relevant to the taxpayer’s business in Malaysia. Alternatively, the taxpayer can attach the Master file prepared by the Group or ultimate holding company with the Local TPD.
  • Previously this requirement was only applicable for Group of Companies that is required to submit the Country-by-Country Report.
  • In the absence of any Master File, the local taxpayer will have to request for this information from the ultimate parent company to include in the Local TPD.
  • The Tax Authorities have also included a detailed list of information and/or documentation to be included or attached in the Local TPD.
  • Based on the above, taxpayers must indicate in the TPD if any of the information or documents required are not applicable to the taxpayers. Failure to do so will result in an incomplete TPD.
No longer need to follow the hierarchy of TP methods
Director General has the power to review and replace selected TP method
  • Previously the Guidelines requests taxpayers to select the TP method on a hierarchy basis which means that the Comparable Uncontrolled Price (“CUP”) must be considered first before the other methods on the list.
  • However, now the requirement is that the best method is selected and can be supported by explanation and sufficient reasoning to justify the selection.
  • There is also a clause that allows the Director General to disregard the taxpayer’s selected method and replace with a different method if they are the opinion that it is not the most appropriate method.
Definition of arm’s length range from 37.5 percentile to 62.5 percentile
TP adjustment can be done to median or above if price is not arm’s length
  • The Tax Authorities general practice or expectation previously was for taxpayers to achieve results that is above the median of the benchmarking analysis or to make an adjustment to the median of the benchmarking.
  • The new rules have included a definition for the arm’s length range from 37.5 percentile to 62.5 percentile and that Companies’ who fall within the range may be regarded as arm’s length.
  • However, taxpayers should be aware that the Director General has the power to make any TP adjustment to the median or any other point above median and within the arm’s length range if there is reason to believe that the comparable companies selected is not suitable.
Use of multiple year data to justify the effect on business
  • The Director General may allow for use of data from the review period and prior years if it can be proven that life cycles or business cycles of the property/services are not impacted by the conditions of commercial or financial relations between associated persons.
  • However, this can only be used to assist in the selection of comparable and not for the use of multiple year averages.
14 days dateline to submit TPD upon request
  • Previously this dateline was only included in the TP Guidelines. It has not been included in the Rules as well.
  • Failure to submit the TPD within 14 days will result in penalties even if there is no adjustments made or additional taxes payable.
Focus on importance of DEMPE analysis
  • Emphasizes the importance of the Development, Enhancement, Maintenance, Protection and Exploitation (“DEMPE”) analysis for intangible property.
  • Any party that contributes to the functions above should be entitled to an arm’s length consideration, regardless of legal ownership.

TP Rules 2023 – Additional Requirements

Intra-group Services

Intra-group services are those services rendered between associated persons. A person should be able to exhibit that the intra-group services have been rendered and the provision of such services generates an economic benefit or commercial value to his business and the charge for the intra-group services is justified.

Intra-group services shall be disregarded if it involves:

  • Shareholder or custodial activities
  • Duplicative services
  • Services that provide incidental benefits or passive association benefits
  • On-call services

Cost contribution arrangement

When a person engages in a cost contribution arrangement with a related party to share the costs and risks of a controlled transaction, the person should ensure that the allocation of costs for such arrangement is comparable to how two unrelated parties would have done the allocation at arm’s length in a similar arrangement.

Intangible property

Intangible property refers to an asset which is neither a physical asset nor a financial asset but such asset is capable of being owned or controlled for use in commercial purposes, whose use or transfer would be compensated had it occurred in a transaction between independent persons in comparable circumstances which includes patent, invention, formula, process, design, model, plan, trade secret, know-how or marketing intangible.

Any party that contributes to the functions above should be entitled to an arm’s length consideration, regardless of legal ownership.

Interest on financial assistance

The TP Rule stipulates that all financial assistance is subject finance charge, discount, premium or other consideration relating to a controlled transaction.

Any person in a controlled transaction who provides or receives financial assistance (i.e. loan, interest bearing trade credit, advance or debt), directly or indirectly, to or from another person with or without consideration, shall determine the arm’s length interest rate for such assistance.

TP Guidelines 2024

On 30 December 2024, the IRBM issued the Malaysian Transfer Pricing Guidelines 2024 (“TP Guidelines 2024”), which take effect from the YA 2023. These updated guidelines are to be read together with the Income Tax Act 1967 and the 2023 TP Rules. Key changes include expanded guidance and new requirements for contemporaneous transfer pricing documentation (“CTPD”).

Scope for preparation of CTPD

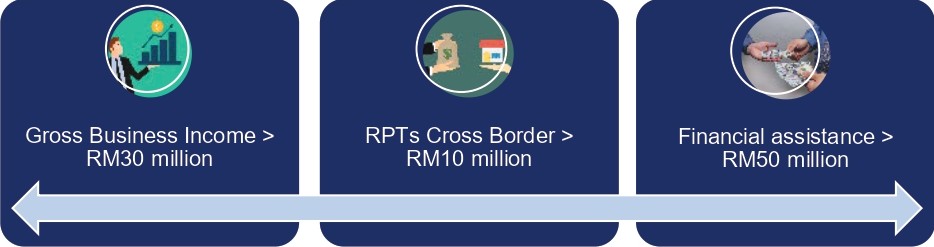
In the transfer pricing guidelines 2024, the IRBM further relaxed requirements by revising the threshold for preparing full CTPD, as follows:
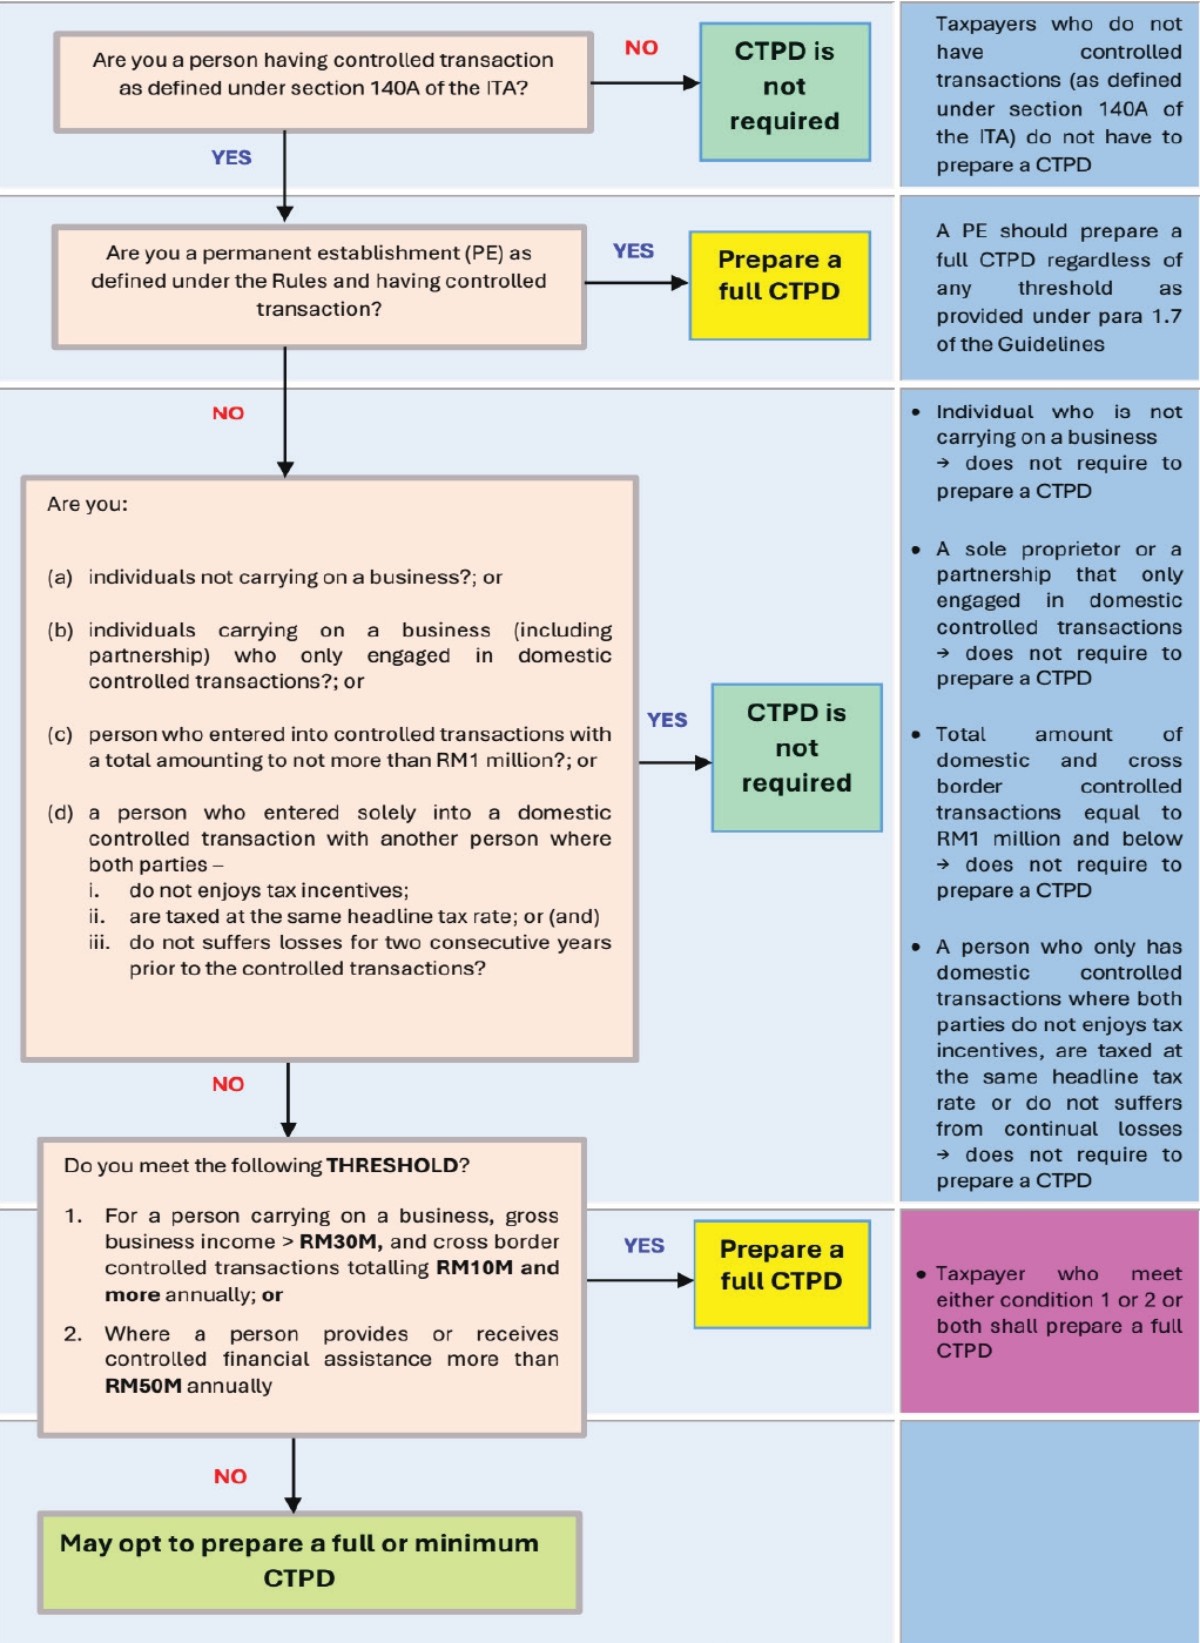
Companies that does not fall within the threshold are allowed to prepare documentation that is less extensive, i.e. Minimum CTPD. A PE shall prepare its own full CTPD separately from its head office and related branches, as specified under the TP Rules.

Exemption for preparing transfer pricing documentation

To ease the compliance burden for taxpayers, the TP Guidelines 2024 excludes the following persons (which include a company, a body of persons and a sole proprietor) from preparing a full or minimum CTPD:
Individual not carrying on a business; or
Individuals carrying on a business (including partnerships) who only engage in domestic controlled transactions; or
Person who entered into controlled transactions with a total amounting to not more than RM 1 million;
Person who entered solely into domestic controlled transactions with another person where both parties; (a) do not enjoy tax incentive (b) are taxed at the same rate; and (c) do not suffer losses for 2 consecutive years.

CTPD Flowchart

CTPD requirements

According to the TP Rules 2023, the IRBM mandates that a CTPD be brought into existence prior to the deadline for filing a Corporate Income Tax (“CIT”) return (i.e. 7 months after the financial year end of the companies, or any extended CIT return filing, in a given YA). The completion date of the TPD must be indicated on the TPD and must be provided within 14 days upon request during a tax audit. Failure to comply with this requirement may result in a penalty ranging between RM20,000 and RM100,000 for each YA under the section 113B of ITA.

Full CTPD Scope

The required contents of a comprehensive full CTPD are outlined in Paragraph 11.7, Chapter 11 of the TP Guidelines 2024, and are aligned with the requirements under the TP Rulesas follows:
a) Group worldwide organizational structure
b) Description of MNE Group businesses
c) MNE’s intangible assets
d) MNE’s intercompany financial activities
e) MNE’s financial and tax position
In the event that a master file has been prepared for the Group, it can be included as an attachment and does not have to be repeated in the report
f) Local organizational structure and company background
g) Nature of business/industry and market conditions
h) Controlled transactions
i) Pricing policies including formula adopted and sample documents to justify
j) Assumption, strategies and information regarding factors that influenced the price setting policies
k) Functions, assets and risk analysis including risk analysis framework
l) Comparability analysis
m) Selection of the transfer pricing method including basis to justify the selection
n) Application of the transfer pricing method
o) Financial information
p) Other relevant/supporting documents.

Minimal TPD Scope

Taxpayers who are eligible to prepare a minimum CTPD are subject to a reduced documentation requirements.

For minimum CTPD, the scope of controlled transactions and pricing policy is limited to key controlled transactions, which are defined as:

  1. Transactions related to the taxpayer’s principal business activity, and
  2. Transactions that, while not principal in nature, individually contribute 20% or more of the taxpayer’s operating revenue for the relevant YA.

The IRB has released a template to simplify TPD compliance and reduce administrative burden of compliance for SMEs (PIN 1/2023). Companies that fall below the threshold can choose to fill in the details requested in the minimum TPD template.

The template is a form that consists of 4 parts as follows:

Company Information

  • Company reg no.
  • Tax reference
  • Address
  • Financial period
  • Principal activity
  • Industry code/ Type of business activity

Group Information

  • Name, Country, Address and Tax No. of Ultimate, Holding Subsidiary and Affiliate Companies
  • Global and Company organization chart
  • Reporting lines

RPTs

  • Type, amount of RPT and percentage of transactions
  • Name, Country, Business activity, Tax No. and relationship of related companies involved in transaction
  • Agreement/ supporting documentation

Policy

  • Pricing policy for each type of RPT
  • Pricing basis (i.e. costs elements & profit mark-up)
  • Sample documentation
  • Comparability study

Low value adding intra-group services (“LVAS”)

The IRB has adopted a simplified approach for LVAS (though this approach is only applicable to Malaysia service providers or foreign service providers who have similarly adopted the Organisation for Economic Co-operation and Development (“OECD”) simplified approach in their jurisdiction).

The service provider shall apply a profit mark-up of 5% to all costs in the pool (expect for any pass- through costs) and the mark-up under this approach does not need to be justified by a benchmarking study. However, all relevant documents should be prepared on the simplified approach.

TP Audit Framework

The IRBM has updated its TP Audit Framework (“TPAF”) over the years to change how tax audits are done. The newest and current version is the TPAF 2025, which came out on 31 July 2025. This version replaced the 2024 Framework which was releases together with the TP Guidelines 2024 to change the way penalty surcharges are calculated for businesses.

Key takeaways of the TPTAF 2025 are as follows:
Key Takeaways Details
Year of assessment The IRB may carry out a comprehensive audit for up to six (6) YAs. However, the Yas covered to raise the assessment may be extended to seven (7) prior years of assessment, depending on the audit findings.
Basis for selection of cases Basis used in the selection of TP tax audit cases is based on:
  • Selection through risk assessment criteria for controlled transactions;
  • Restructuring of the company group; and
  • Information received from third parties including foreign tax authorities.
Audit settlement For TP tax audits that only involve related companies in Malaysia, if there are any adjustments made to any of those related companies, the offsetting adjustment for the same amount will not be automatically given to the other related parties.

The application for an offsetting adjustment must be made by the other related parties, and audits will be carried out to ensure that the application may be considered on the provisions of the Act.
Voluntary disclosure Voluntary disclosures are made after the deadline for submission of the Return Form but before the audit commences.

The information and documentation required, along with the Voluntary Disclosure Form to be submitted is set out and included in the TPTAF 2025.
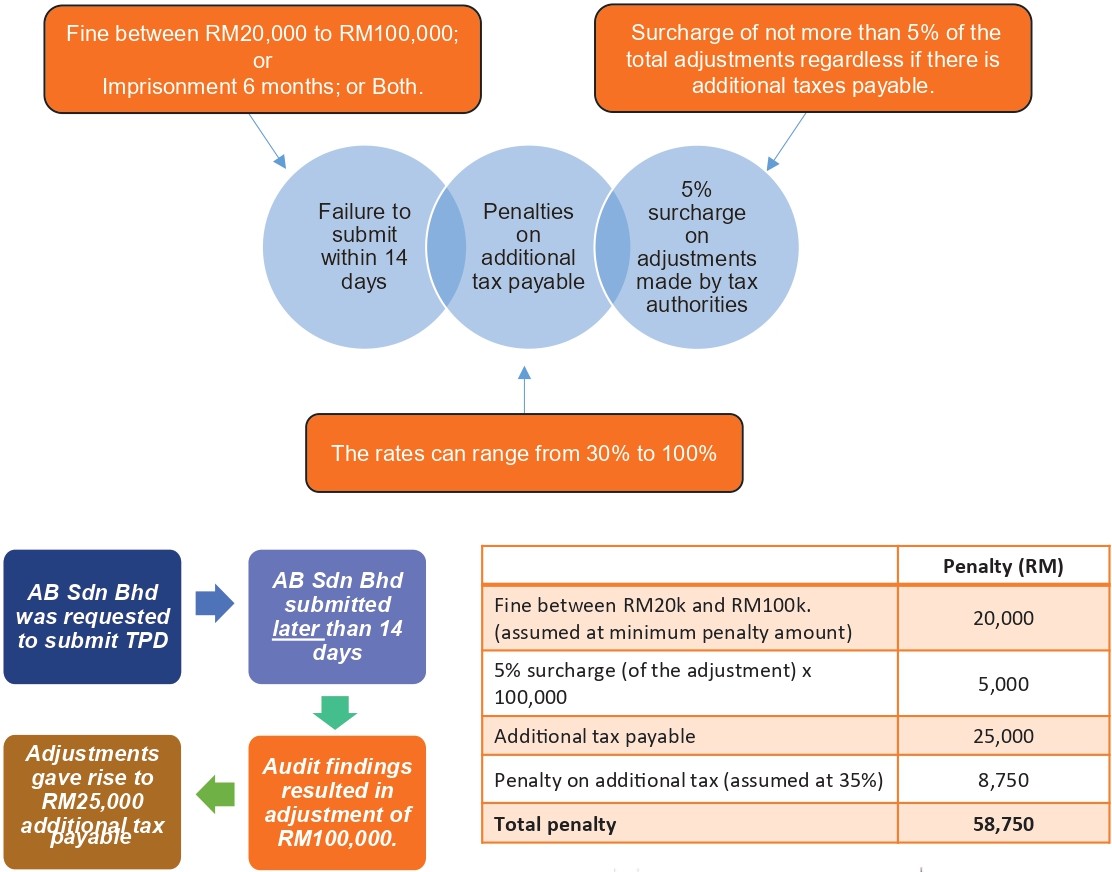
Offence, penalty and surcharge A surcharge at a rate of up to 5% on the amount of the transfer pricing adjustment may be imposed instead (0% to 4% for a voluntary disclosure). A surcharge still may be imposed even if no additional assessment is raised because the surcharge rate is imposed on the amount of the adjustment itself.

Penalty

TPTAF has established a penalty structure for the failure to submit the TPD within the required timeframe as well as for adverse audit findings.

From the year of assessment 2023, a taxpayer who fails to submit a TPD within 14 days from the date of service of a written notice has committed an offence under subsection 113B(1) of the ITA. The taxpayer may be fined not less than RM20,000.00 and not more than RM100,000.00 or imprisonment for not more than 6 months or both.

The amount of penalty that will be imposed based on the period of delay in submitting the TPD is as follows:
No Period of delay (number of days) Penalty amount
1 Up to 7 days RM20,000.00
2 More than 7 days up to 14 days RM40,000.00
3 More than 14 days up to 21 days RM60,000.00
4 More than 21 days up to 28 days RM80,000.00
5 More than 28 days RM100,000.00

Illustration on Penalties

Income Tax (Country-by-Country Reporting) Rules 2016 (“CbyCR Rules”)

The tax authorities issued the CbyCR Rules followed by the Labuan CbyCR Regulation, effective from 1 January 2017.

The Rule is applicable to MNE Groups that fulfil the following criteria:
Income Tax (CbyCR) Rules 2016
Total consolidated group revenue
  • RM 3 Billion
Constituent entities
  • Ultimate holding entity; or

  • Incorporated under the companies act 2016; or

  • Surrogate holding entity; or

  • Permanent establishment in Malaysia.

Labuan Business Activity Tax (CbyCR) Regulations 2017
Total consolidated group revenue
  • RM 3 Billion
Ultimate holding / Constituent entities
  • Labuan entity carrying on a Labuan business activity.

Timeline

The rules state that the ultimate parent (reporting entity) would have to complete the CbyC Report and submit it to the tax authorities on or before 12 months from the last day of the reporting FY (i.e. 31 December 2024 if the tax payer’s year end is 31 December 2023).

Penalty under Section 112A & 113A of the ITA and Labuan Regulations

Income Tax (CbyCR) Rules 2016 Labuan Business Activity Tax (CbyCR) Regulations 2017
Failure of submission/Incomplete and/or incorrect information provided to the DGIR:
  • Fine of not less than RM20,000 and not more than RM100,000; and/or
  • Imprisonment of not exceeding 6 months.
Failure of submission/Incomplete and/or incorrect information provided to the DGIR:
  • Fine of not exceeding RM1,000,000; and/or
  • Imprisonment of not exceeding two years.
Additionally, there is also a requirement for the Malaysian Companies to notify the tax authorities under Subrule 6(1) and 6(2) of the PU (A) 357/2016 either by disclosing the information as part of the tax returns or by submitting the manual notification form.

Malaysian parent entities and subsidiaries submitting the Form C , TR , TA , TC or TN (tax return forms, whichever is applicable) can furnish the notification by way of tax returns while companies filing Form LE & TF are required to furnish the notification using a manual notification form as follows:
Reporting entity
[Annex B1]
The reporting entity shall notify the Director General in writing if it is the ultimate holding entity on or before the last day of the FY.
Details of all Malaysian and foreign non-reporting constituent entities must be included.
Non-reporting entity
[Annex C1 & C2]
The Malaysian subsidiary must notify the Director General in writing of the identity and tax residence of the reporting entity on or before the last day of the FY.

Tax Return Form

Throughout the year from FY 2014 to FY 2022, the income tax return form has been amended to include additional disclosures as follows:

  1. Transfer Pricing Documentation and its related information

    Tax payer is to disclose its characterization, other related information and all type of transactions they are involved in with a related party and the amount.

  2. Disclosure of whether the taxpayer is subject to interest restriction under Section 140C.

    Tax authorities introduced Restriction on deductibility of interest under Section 140C of the Income Tax Act 1967, effective 1 July 2019 onwards aimed at restricting the deduction of interest expense in relation to cross border transaction. The Rules are applicable to:

    • companies who have been granted any financial assistance in a controlled transaction;
    • the total amount of any interest expense for all such financial assistance exceeds RM500,000 in the basis period.

    The maximum amount of interest that is deductible is 20% of the Tax EBITDA. The balance is allowed to be carried forward.

  3. Disclosure on CbyCR

    Tax payer is to disclose if CbyCR is relevant for the Group and fill in the relevant information of the reporting entity.

Key Take-aways

  • Tax authorities may enforce a tax audit at any time of the year.
  • Tax authorities have provided a time and cost-efficient template for SME companies to encourage
  • compliance.
  • In addition to the template, taxpayers also need to include documentation or analysis to justify that
  • the RPT is carried out at market price (i.e. comparability study)
  • It is essential for the taxpayers to indicate the completion date on the TPD.
  • Although there are exemptions for the preparation of TPD, in case of an audit, there are possibilities for
  • adjustments that will result in additional tax.
  • There is a risk of IRB imposing the 5% surcharge on adjustments on top of penalty imposed.
  • Taxpayer’s responsibility is to maintain the relevant records, documentation and calculation to justify
  • the arm’s length nature of the inter-company transactions.
  • Taxpayers need to reassess the completeness and robustness of the TPD prepared previously and
  • make amendments to the scope where necessary.
  • Taxpayers should ensure contemporaneous preparation of the TPD.
Categories
Ideas & Insights Newsletter Tax

Employee Secondment Is Free From Service Tax Subject To Certain Conditions

Ideas & Insights

Key Takeaway

A secondment arrangement is not automatically non-taxable. Its Service Tax treatment depends on whether the applicable conditions for a genuine secondment are satisfied.

Tips

  • Review your existing employee secondment arrangements to ensure they meet the conditions under Ketetapan Umum Bil. 5/2026;
  • Identify arrangements that do not meet the prescribed conditions and assess whether Service Tax should be charged on the relevant employment services.
Under the 2024 Guide on Employment Services, employment services are generally subject to Service Tax. However, employee secondment is excluded from the scope of taxable employment services.

With the issuance of General Ruling Bil. 5/2026, Customs has now clarified what qualifies as an employee secondment. In simple terms, a secondment arrangement will not be subject to Service Tax only if all the prescribed conditions are met.

A secondment arrangement will be regarded as non-taxable services only if all of the following conditions are satisfied:

Appropriate contractual documentation

The arrangement should be supported by a formal secondment agreement or other relevant documentation evidencing the nature and terms of the secondment;

Original employer is not an employment-service provider

The original employer’s business must not be the provision of employment services, including an employment agency or professional employer organisation;

Temporary transfer

The employee is temporarily transferred to perform duties for another company for a specified period and subsequently returns to the original employer;

Continuing employment relationship

The employee remains employed by the original employer, with the employment relationship continuing throughout the secondment;

Exclusive service during secondment

During the secondment period, the employee works solely for the host company;

Control by the host company

The host company has overall control over the employee’s work and duties during the secondment; AND

Salary / allowances recovered at cost only

The host company bears the employee’s remuneration and relevant allowances, whether paid directly or indirectly, without an additional service fee, commission or mark-up.
Categories
Ideas & Insights Newsletter Tax

e- Invoice: RM3 Million Is the New Threshold!

Ideas & Insights

Key Takeaway

e-Invoice exemption threshold increased from RM1 million to RM3 million, effective 1 September 2026.

Tips

  • Check your annual turnover/revenue against the RM3 million threshold.
  • Check ownership and group structures before relying on the exemption, particularly shareholders, holding companies, related companies and joint ventures.
The Inland Revenue Board of Malaysia (“IRBM”) issued e-Invoice Guideline Version 4.8 on 30 August 2026, replacing Version 4.7 dated 7 July 2026. The key amendments relate principally to the e-Invoice implementation timeline and the exemption threshold for taxpayers with annual turnover or revenue below RM3 million.

This represents a significant relaxation for taxpayers with turnover between RM1 million and below RM3 million, who were previously within the e-Invoice framework.

The amendments comprise changes to paragraphs 1.5 and 1.6.1(e), together with the introduction of new paragraphs 1.6.9 and 1.6.10 as below:

Implementation timeline for new businesses

Paragraph 1.5 has been amended to reflect the revised RM3 million threshold in determining the e-Invoice implementation timeline for businesses that commence operations between 2023 and 2025. Businesses that commenced operations during this period should reassess their e-Invoice implementation date based on the revised RM3 million threshold.

Exemption threshold increased

The exemption threshold has been increased from RM1 million to RM3 million.

Specific taxpayers brought into the e-Invoice requirement

This Guide further clarifies the e-Invoice treatment applicable to the following entities:

  • Statutory bodies;
  • Statutory authorities;
  • Local authorities; and
  • International organisations.

These entities are required to issue e-Invoices for goods sold or services performed from 1 July 2025 onwards.

Conditions restricting the RM3 million exemption

The exemption for taxpayers with annual turnover / revenue of less than RM3 million applies across taxpayer categories, including individuals, partnerships, companies and cooperatives. However, the exemption does not apply in certain ownership or group-structure circumstances:-

Taxpayer with annual turnover or revenue of less than RM3 million shall not be eligible for the exemption where any of the following conditions apply:

  • Non-individual shareholder
    The taxpayer has a non-individual shareholder (or equivalent) with annual turnover / revenue of RM3 million or more.
  • Subsidiary
    The taxpayer is a subsidiary of a holding company whose annual turnover / revenue is RM3 million or more.
  • Related company / joint venture
    The taxpayer has a related company or joint venture with annual turnover / revenue of RM3 million or more.
Categories
Ideas & Insights Newsletter Tax

Employment Service: Fees Subject Service Tax While Salary Recoveries, Disbursement Costs & Statutory & Regulatory Charges Are Excluded

Ideas & Insights

Key Takeaway

Service Tax applies only to employment or management fees, excluding disbursement expenses.

Tips

To ensure that fees and disbursements are clearly stated and properly supported by documentation.
The Royal Malaysian Customs Department (“RMCD”) issued a new announcement on 13 August 2026, clarifying the Service Tax treatment of employment services, particularly with regard to employment / management fees and disbursement expenses.

Under the RMCD’s clarification:

  • Employment or Management fees
    Service Tax applies to the fees charged for the provision of employment services and management services;
  • Disbursement Costs
    Costs or expenses incurred on behalf of a customer and subsequently recovered on a pass-through (disbursement) basis are not subject to Service Tax;
  • Statutory and regulatory charges
    Fees, duties, levies, taxes, fines, penalties and other similar payments imposed under written laws and paid on behalf of the customer are treated as disbursements. These amounts should not be included in the taxable value for Service Tax purposes.
Categories
Ideas & Insights Newsletter Tax

Employment Contracts of RM3,000 and Below No Longer Require IRBM Endorsement

Ideas & Insights

Key Takeaway

Not every employment-related document needs to be stamped.

Tips

Check the employment contract and related documents against the applicable category to determine whether stamp duty payment, stamping, or endorsement is required.
The Inland Revenue Board of Malaysia (“IRBM”) issued a media release on 7 August 2026 providing important guidance on stamp duty for employment contracts, including the applicable exemptions and endorsement requirements under the Stamp Act 1949.

At a Glance: Do You Need to Stamp Your Employment Documents

Employment Document / Situation What Employers Need to Do
Employment contract with monthly salary of RM3,000 or below. No stamping and no endorsement required.
Employment contract with monthly salary above RM3,000. Stamp and endorse only the main/master employment contract.
Supporting employment documents relating to the same employment. No stamping and no endorsement required.
Instrument covered under the “General Exemption” category. No stamp duty payable, but endorsement is required.
For more details, please click the link below:
Media Release dated 07 August 2026
Categories
Featured Ideas & Insights Publications US Desk

SEC Filer Categories and Filing Deadlines for U.S. Domestic Issuer vs Foreign Private Issuer (FPI)

Ideas & Insights

SEC reporting requirements and filing deadlines differ based on a company’s filer category and issuer status. Understanding the distinctions between U.S. Domestic Issuers and Foreign Private Issuers (FPIs) is essential for maintaining compliance with applicable SEC reporting obligations.

1. Large Accelerated Filer

Definition A company is a Large Accelerated Filer if it:

  1. Has a public float of US$700 million or more;
  2. Has been subject to SEC reporting requirements for at least 12 calendar months;
  3. Has filed at least one annual report (Form 10-K); and
  4. Is not eligible as a smaller reporting company under certain SEC tests.

Public Float
Public float means:
The aggregate worldwide market value of voting and non-voting common equity held by non-affiliates (public shareholders).

Usually calculated as:
Share price × publicly held shares
Measured on the last business day of the company’s second fiscal quarter.

Filing Deadline for U.S. Domestic Issuer
  • Form 10-K: within 60 days after fiscal year-end
  • Form 10-Q: within 40 days after quarter-end

2. Accelerated Filer

Definition A company is an Accelerated Filer if it:

  1. Has a public float of US$75 million to less than US$700 million;
  2. Has been reporting with the SEC for at least 12 months;
  3. Has filed at least one annual report; and
  4. Does not qualify as a Large Accelerated Filer.

Filing Deadline for U.S. Domestic Issuer
  • Form 10-K: within 75 days after fiscal year-end
  • Form 10-Q: within 40 days after quarter-end

3. Non-Accelerated Filer

Definition A company is a Non-Accelerated Filer if it:

  1. Has a public float below US$75 million; OR
  2. Does not yet meet the SEC reporting history requirements for accelerated filer status.

This category commonly includes:

  • Newly public companies
  • Small-cap issuers
  • Early-stage issuers

Filing Deadline for U.S. Domestic Issuer
  • Form 10-K: within 90 days after fiscal year-end
  • Form 10-Q: within 45 days after quarter-end

4. Summary Table

Category Public Float 10-K Deadline 10-Q Deadline
Large Accelerated Filer≥ US$700M60 days40 days
Accelerated FilerUS$75M – < US$700M75 days40 days
Non-Accelerated Filer< US$75M90 days45 days
Filing Deadline for Foreign Private Issuer (FPI)
Current SEC Rule: Most FPIs filing Form 20-F must file within 4 months after fiscal year-end, this applies broadly to FPIs regardless of accelerated filer status.

Which Filer Categories Are Subject to SOX for both U.S. Domestic and Foreign Private Issuer (FPI)?

Category SOX Applies? External Auditor ICFR Attestation Required?
Large Accelerated Filer Yes Yes
Accelerated Filer Yes Yes
Non-Accelerated Filer Yes Generally exempt from SOX 404(b) auditor attestation
SOX compliance refers to compliance with the Sarbanes-Oxley Act (“SOX”), a U.S. federal law enacted in 2002 after major accounting scandals such as:
  • Enron Corporation
  • WorldCom

The purpose of SOX is to:
  • Improve corporate governance
  • Enhance financial reporting reliability
  • Strengthen internal controls
  • Protect investors from fraud

SOX applies to companies listed in the U.S. and regulated by the Securities and Exchange Commission (SEC).

Key SOX Compliance Requirements

1. Internal Control Over Financial Reporting (ICFR)

Companies must establish and maintain effective internal controls over:

  • Financial reporting
  • Accounting processes
  • Disclosure controls


Important Distinction — SOX 302 vs SOX 404

SOX Section 302
Applies to almost all SEC reporting companies:

  • CEO/CFO certification
  • Disclosure controls


SOX Section 404(a)
Management must assess internal controls.

SOX Section 404(b)
External auditor attestation on ICFR effectiveness.
This 404(b) requirement mainly applies to:

  • Large Accelerated Filers
  • Accelerated Filers


Non-accelerated filers are generally exempt.

Simplified Summary

Item Large Accelerated Accelerated Non-Accelerated
SOX AppliesYesYesYes
CEO/CFO CertificationYesYesYes
Internal Control AssessmentYesYesYes
External Auditor ICFR OpinionYesYesUsually No
Compliance BurdenHighestHighLower
Categories
Featured Ideas & Insights Publications US Desk

Nasdaq Private Market vs Nasdaq Capital Market

Ideas & Insights

Understanding the key differences between these two platforms, Nasdaq Private Market and Capital Market are essential for companies evaluating their fundraising, liquidity, governance, and long-term growth strategies.
While both Nasdaq Private Market and Nasdaq Capital Market provide avenues for companies to access capital and liquidity opportunities, they serve fundamentally different purposes and stages of a company’s growth journey.

Nasdaq Private Market is designed for private companies seeking to facilitate secondary transactions and shareholder liquidity without becoming publicly listed, whereas Nasdaq Capital Market is a public stock exchange tailored for smaller-cap companies that wish to access the public capital markets. Understanding the key differences between these two platforms are essential for companies evaluating their fundraising, liquidity, governance, and long-term growth strategies.
Item Nasdaq Private Market Nasdaq Capital Market
NaturePrivate market / secondary liquidity venuePublic stock exchange
Company StatusPrivate companiesPublic listed companies
SEC Registration as Public CompanyNot required (generally)Mandatory
Public TradingNoYes
IPO RequiredNoYes (or direct listing/SPAC)
Investor AccessMostly accredited / institutional investorsOpen to public investors
LiquidityLimited / event-drivenContinuous daily trading
Valuation TransparencyLimitedHigh transparency
Item Nasdaq Private Market Nasdaq Capital Market
Share Price VisibilityNegotiated privatelyReal-time public pricing
Disclosure LevelLimited private disclosuresFull SEC disclosure
Financial ReportingUsually private-company standardSEC reporting (10-K, 10-Q, 8-K)
Corporate Governance RulesFlexibleStrict Nasdaq governance rules
Market MakersNot applicableMinimum 3 market makers
Public Float RequirementNo formal public floatYes
Public Shareholders RequirementNo public spread requirementYes
Minimum Bid PriceNo exchange bid-price ruleUsually US$4 initial listing
Delisting RiskMinimal exchange riskSubject to Nasdaq compliance rules
Trading MechanismTender offers, auctions, block tradesExchange order book
Typical UsersUnicorns, startups, pre-IPO firmsSmall-cap public companies
ExamplesOpenAI secondary, SpaceX secondary type dealsSmall-cap biotech, tech, growth companies

Key SEC / Regulatory Difference

Item Nasdaq Private Market Nasdaq Capital Market
Securities Act RegistrationUsually exemptRequired
Exchange Act RegistrationOften exemptMandatory
Main SEC Filings Form D (Private fundraising, venture rounds, private placement offerings), Form 144 (Affiliates/insiders resell restricted securities, usually applies to: founder sales, investor secondary sales), Schedule TO "tender offer" docs (organized tender offer, company-sponsored liquidity event) S-1/F-1, 10-K, 10-Q, 8-K
Trading Venue RegulationATS / broker-dealer rulesNational securities exchange
Sarbanes-Oxley ComplianceUsually not required fullyRequired
PCAOB Audit RequirementOften not mandatoryMandatory

Practical Business Difference

Nasdaq Private Market
Best for:
  • Unicorns delaying IPO
  • Employee liquidity programs
  • Founder/investor secondary sales
  • Controlled shareholder base
  • Less disclosure burden

Typical companies:
  • Late-stage startups
  • Venture-backed tech firms
  • Companies wanting liquidity without going public

Nasdaq Capital Market
Best for:
  • Companies seeking public capital raising
  • Companies needing liquidity + visibility
  • M&A currency (public shares)
  • Institutional investor access

Typical companies:
  • Small-cap biotech
  • Growth technology companies
  • Foreign issuers entering U.S. capital markets

Cost & Compliance Comparison

Item Nasdaq Private Market Nasdaq Capital Market
Legal CostModerateHigh
Audit RequirementFlexibleExtensive
Investor RelationsLimitedContinuous
Quarterly ReportingUsually noYes
Annual Proxy FilingNoYes
SOX Internal ControlsUsually noYes
Listing FeesLowerHigher
Ongoing Compliance CostLowerSignificant
Categories
Featured Ideas & Insights Publications US Desk

Nasdaq – U.S. Domestic Issuer vs Foreign Private Issuer (FPI)

Ideas & Insights

Companies seeking a Nasdaq listing must determine whether they qualify as a U.S. Domestic Issuer or a Foreign Private Issuer (FPI). This classification affects reporting obligations, corporate governance requirements, disclosure standards, and ongoing compliance responsibilities under U.S. securities laws.

1. Definitions

Item U.S. Domestic Issuer ("Local Issuer") Foreign Private Issuer (FPI)
Definition A company organized/incorporated in the U.S. A company incorporated outside the U.S. that qualifies as an FPI under SEC rules
Governing Rule U.S. domestic reporting company SEC Rule 405 / Exchange Act Rule 3b-4
Key Test Incorporated in U.S. Incorporated outside U.S. AND does NOT fail FPI tests
FPI Disqualification N/A Becomes non-FPI if: >50% voting shares held by U.S. residents AND any of below apply: 1) majority directors/officers are U.S. citizens/residents, 2) >50% assets in U.S., or 3) business principally administered in U.S.

2. IPO Filing Forms

Purpose U.S. Domestic Issuer Foreign Private Issuer
Initial IPO Registration Form S-1 Form F-1
Short-form shelf registration (seasoned issuers) Form S-3 Form F-3
Registration for M&A/share exchange Form S-4 Form F-4
Exchange Act registration Form 10 Form 20-F (registration/annual)

3. Main IPO Registration Forms

U.S. Domestic Issuer — For m S-1
Used by U.S. companies conducting IPOs.

Key Contents:
  • Prospectus
  • Audited financial statements
  • MD&A
  • Risk factors
  • Use of proceeds
  • Executive compensation
  • Shareholding structure

Foreign Private Issuer — Form F-1
Equivalent of S-1 for foreign companies.

Differences vs S-1:
  • May use:
    • IFRS as issued by IASB (without US GAAP reconciliation in many cases)
    • Home-country governance exemptions
  • Executive compensation disclosure often lighter
  • Less frequent ongoing reporting obligations post-IPO

4. Post-IPO SEC Reporting Obligations

Ongoing Reporting Comparison

Filing Requirement U.S. Domestic Issuer Foreign Private Issuer (FPI)
Annual Report Form 10-K Form 20-F
Quarterly Report Form 10-Q Not required, but Form 6-K is often used by FPI to furnish interim financial statement that: is made public in their home country, filed with foreign stock exchanges, or distributed to shareholders.
Current Material Event Report Form 8-K Form 6-K
Proxy Statement Schedule 14A Often exempt from U.S. proxy rules
Insider Ownership Filing Forms 3, 4, 5 Usually exempt
FD Fair Disclosure Rules Applies Generally exempt
US GAAP Requirement Yes IFRS permitted
Filing Frequency More frequent Less burdensome

5. Key SEC Forms After IPO

U.S. Domestic Issuer
FormDescription
10-KAnnual audited report
10-QQuarterly financial report
8-KMaterial event disclosure
DEF 14AProxy statement
Forms 3/4/5Insider ownership reporting
S-8Employee stock plans
S-3Secondary offerings / shelf registration

Foreign Private Issuer

FormDescription
20-FAnnual report
6-KMaterial updates/interim disclosures
F-3Shelf registration
F-4M&A/share exchange transactions
F-6ADR registration
13D / 13GBeneficial ownership filings (where applicable)

6. Current Reporting — 8-K vs 6-K

Item Form 8-K Form 6-K
Used By U.S. Domestic issuers FPIs
Filing Trigger Mandatory specific events Furnishing material information made public in home market
Timing Usually within 4 business days Promptly after disclosure
Prescriptive? Highly prescriptive More flexible

Examples:

  • Acquisition
  • CEO resignation
  • Bankruptcy
  • Material agreement
  • Earnings release

7. Financial Reporting Standards

Item U.S. Domestic Issuer Foreign Private Issuer (FPI)
Accounting Standard US GAAP mandatory IFRS accepted
PCAOB Audit Required Required
Currency USD usually Foreign currency permitted

8. Corporate Governance Differences

Topic U.S. Domestic Issuer Foreign Private Issuer (FPI)
Nasdaq/NYSE Governance Full compliance May follow home-country practices
Independent Directors Strict rules Some exemptions
Shareholder Approval Rules Full compliance Certain exemptions

9. ADR Structure (Common for Foreign Issuers)

Many FPIs list in U.S. through:
  • ADR (American Depositary Receipt)

Relevant form:
  • Form F-6

Examples:
  • Alibaba Group
  • Toyota Motor Corporation
  • Grab Holdings

10. Why Many Foreign Companies Prefer FPI Status

Advantages
  • Less frequent reporting
  • No quarterly 10-Q
  • IFRS accepted
  • Reduced executive compensation disclosure
  • Home-country governance exemptions
  • Reduced insider reporting burden

Disadvantages
  • Some U.S. investors prefer domestic issuer transparency
  • May trade at lower valuation multiple in certain sectors
  • Potential governance perception issues

11. Quick Summary Table

Topic Domestic Issuer Foreign Private Issuer
IPO Form S-1 F-1
Annual Report 10-K 20-F
Quarterly Report 10-Q None
Current Report 8-K 6-K
Accounting Standard US GAAP IFRS allowed
Insider Forms 3/4/5 Usually exempt
Governance Rules Full U.S. rules Partial exemptions
Reporting Burden Higher Lower
Categories
Ideas & Insights Newsletter Tax

Stamp Duty – Special Voluntary Disclosure Programme

Ideas & Insights

Key Takeaway

  • Responsibility for stamp duty assessment is now placed on taxpayers.
  • Taxpayers are afforded the chance to regularize unstamped instruments and seek remission of penalties.
Many businesses are unaware that certain agreements — including loan agreements, service contracts and shareholders’ agreements — may be subject to stamp duty. The introduction of the Stamp Duty Self-Assessment System and the Special Voluntary Disclosure Programme makes it timely for businesses to review their documenta- tion and ensure compliance.

Stamp duty is a tax imposed on certain of written instruments specified in the First Schedule of Stamp Duty Act 1949 (“SA”) and not on the underlying transactions themselves.

There are two main categories of stamp duty:

  1. Ad valorem duty – calculated based on the type and value of the instrument; and
  2. Fixed duty – imposed at a prescribed amount, typically starting from a nominal sum of RM10 per instrument.

STAMP DUTY SELF-ASSESSMENT SYSTEM (SDSAS)

Effective from 1 January 2026, the Inland Revenue Board of Malaysia (“IRBM”) has implemented the Stamp Duty Self-Assessment System. The implementation will be carried out in phases as follows:-
Phase Effective Date Type of Instruments
Phase 1 From 1 January 2026 Instruments or agreements relating to rentals or leases, general stamping and securities.
Phase 2 From 1 January 2027 Instruments for transfer of property ownership.
Phase 3 From 1 January 2028 Instruments or agreements not covered under Phase 1 and Phase 2.

RESPONSIBITIY OF DUTY PAYERS

Under SDSAS, taxpayers are responsible for determining, calculating and declaring stamp duty obligations. For instruments executed in Malaysia, they must be stamped within 30 days of the date of execution. For instruments executed outside Malaysia, the instrument must be stamped within 30 days from the date it is first received in Malaysia.

Taxpayers are also required to retain the stamped instruments and all related supporting documents for a minimum period of seven (7) years to ensure proper compliance and to facilitate any audit by IRBM.

PENALTIES

Late Stamping
Period of Delay in Stamping Penalties
Not exceeding 3 months RM50 or 10% of the duty amount (whichever is higher)
Exceeding 3 months RM100 or 20% of the duty amount (whichever is higher)
Executing or Signing Unstamped Documents
Any person who executes or signs an instrument that has not been duly stamped may be liable to a fine of not less than RM1,000 and not exceeding RM10,000

SPECIAL VOLUNTARY DISCLOSURE PROGRAMME (“SVDP”) FOR STAMP DUTY

On 28th January 2026, the IRBM has announced a Special Voluntary Disclosure (‘SDVP’) for stamp duty and published a set of Frequently Asked Questions (“FAQs”) in relation to SVDP on its website.

During SDVP period from 1 January 2026 to 30 June 2026, all instruments executed from 1 January 2023 to 31 December 2025 may qualify for penalty exemption under Section 47A(2), Stamp Act 1949, subject to relevant conditions.

Key Points from the FAQ

  1. Instruments executed between 1 January 2023 and 31 December 2025 are eligible for SVDP 2026, provided that stamping and payment of stamp duty payment are completed between 1 January 2026 and 30 June 2026;
  2. Eligible for SDVP 2026:-
Stamping Submission Date Status of Stamp Duty Payment Status of Penalty
Before 1 January 2026 Fully paid (including penalties) Not eligible for SDVP
Before 1 January 2026 No payment made within the SVDP period Penalty not waived
1 January 2026 – 30 June 2026 Payment made within the SVDP period Penalty waived
  1. No appeal application is required and penalty will be automatically waived once the stamp duty is paid between 1 January 2026 to 31 December 2026;
  2. All instruments executed between 1 January 2023 and 31 December 2025 and stamped under SVDP 2026 will not be subject to audit. However, SVDP does not prevent the IRBM from auditing other instruments not disclosed under the SVDP;
  3. Cases involving fraud are excluded from the SVDP programme.
The FAQs are available in Bahasa Malaysia and can be downloaded from the IRBM’s official website:-
FAQs

Action Points for Business

Businesses should consider taking the following steps:
1. Conduct an Internal Review of Documents
Businesses should review all contracts and written instruments executed between 1 January 2023 and 31 December 2025 to determine whether they are subject to stamp duty but have not been stamped.

Common examples include:
  • Rental or tenancy agreements
  • Service agreements
  • Loan agreements between companies or related parties
  • Shareholders’ agreements
  • Security documents (charges, debentures, guarantees)
  • Memorandum of understanding (MOU) with binding terms
  • Settlement agreements

2. Identify Unstamped or Late-Stamped Instruments
Businesses should identify documents that:
  • have not been stamped, or
  • were stamped after the statutory deadline.

These may qualify for penalty exemption under the SVDP if disclosed within the programme period.

3. Take Advantage of the SVDP Window
Where unstamped instruments are identified, businesses should submit the documents for stamping and pay the applicable stamp duty before 30 June 2026 to enjoy full penalty waiver.

4. Strengthen Internal Compliance Procedures
With the implementation of SDSAS, businesses should implement internal procedures to ensure that:
  • new agreements are reviewed for stamp duty implications;
  • stamping deadlines are monitored; and
  • supporting documentation is properly maintained.

5. Seek Professional Advice Where Necessary
Businesses that are uncertain whether a document is subject to stamp duty should seek professional advice, as incorrect stamping or failure to stamp instruments may result in penalties.
If you would like assistance in reviewing your agreements or determining whether any instruments require stamping, please feel free to contact us.